
Skip to content

Joint Arrangements (IFRS 11)

VIVA Subject Guide
YouTube video

A joint arrangement is an arrangement where two or more parties have joint control over an entity under a contractual agreement.

  • Joint venture

  • Joint operation

Each party will normally have a right of veto over key decisions.

Joint venture

A joint venture is whereby the parties have rights to the net assets of the arrangement. A separate entity is created and each of the venturers hold shares in the new entity.

The accounting for the arrangement is done using equity accounting.

Joint operation

A joint operation is whereby the parties have rights to the assets and obligations for the liabilities of the arrangement

The accounting for the arrangement is done by each party recording their share of the arrangements assets and liabilities in their own statement of financial position and their share of revenue and costs in their own statement of profit or loss.
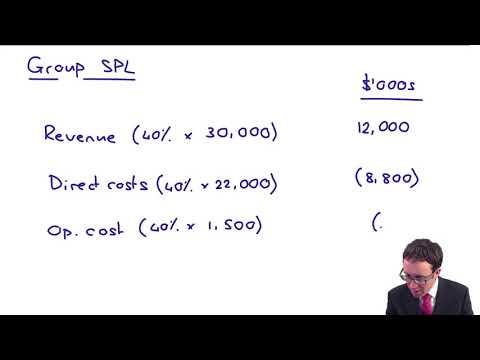
YouTube video

Example 1 – Joint operation

Lyon has a 40% share of a joint operation, a natural gas station. The following information relates to the joint arrangement activities:

  • The natural gas station cost $15 million to construct and was completed on 1 January 2015. Its useful life is estimated at 10 years.

  • In the year, gas with a direct cost of $22 million was sold for $30 million. Additionally, the joint arrangement incurred operating costs of $1.5 million during the year.

  • Assets, liabilities, revenue and costs are apportioned on the basis of the shareholding.

Lyon has only contributed and accounted for its share of the construction cost, paying $6 million. The revenue and costs are receivable and payable by the other joint operator who settles amounts outstanding with Lyon after the year-end (31 December 2015)

Show how Lyon would account for the above in its consolidated financial statements for the year ended 31 December 2015.

Show answerHide answer

Example Answer 1 – Joint operation

Lyon statement of profit or loss for the year-ended 31 December 2015

$’000$‘000 40%
Revenue
Costs – direct
Costs – operating
Depreciation (15,000 / 10 years)
Profit

Lyon statement of financial position as at 31 December 2015

$’000
PPE (6,000 – 600)
Receivables
Payables (8,800 + 600)