Skip to contentSkip to search

Inventory (IAS 2) and Agriculture (IAS 41)

VIVA Subject Guide

1 Inventory (IAS 2)

YouTube video
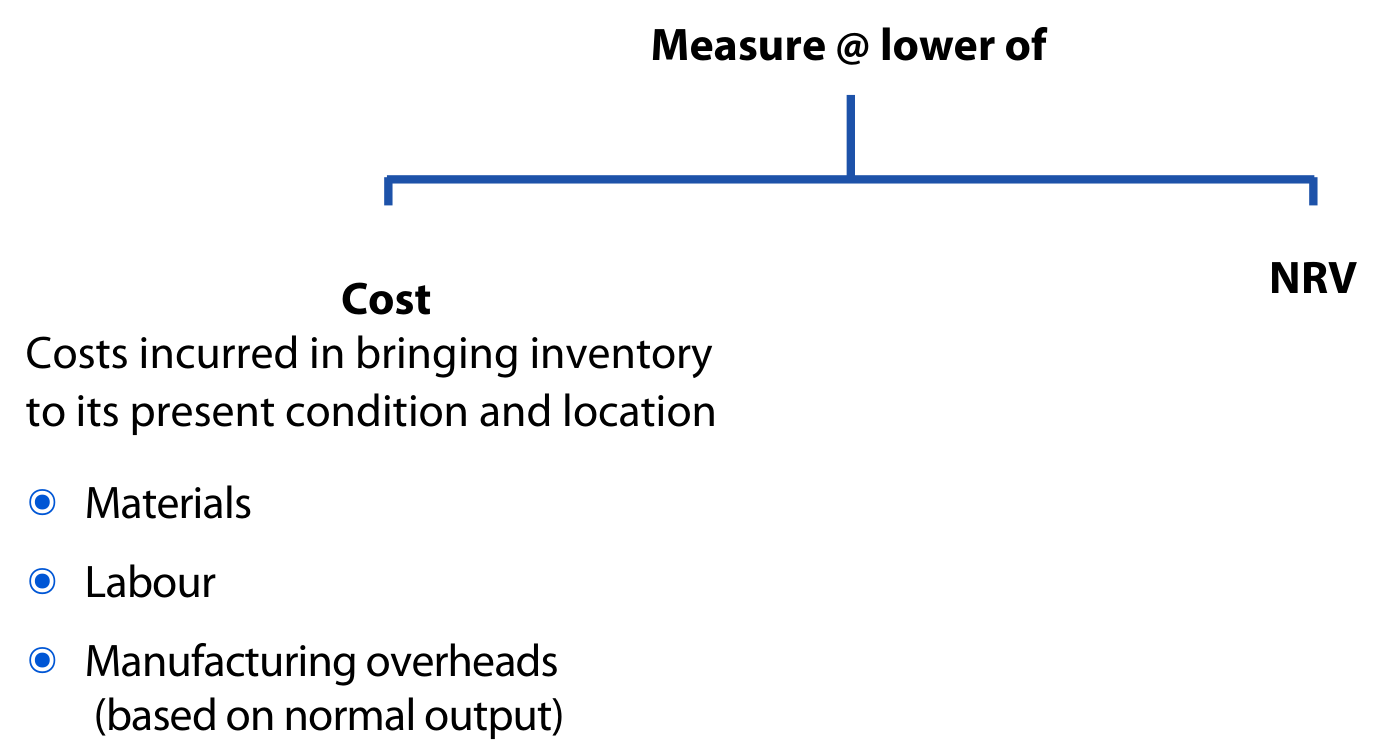
Inventory measured at the lower of cost and NRV

Selling price

X

Less:

Costs to complete

(X)

Costs of selling

(X)

NRV

X

Practice question

Under IAS 2 Inventories, consider the following costs of a manufacturing entity:

(1) Carriage inwards

(2) Carriage outwards

(3) Depreciation of factory plant

(4) General administrative overheads

Which costs should be included in the cost of inventory?

YouTube video

Example 2 – Inventory (valuation)

Neil paid $3 per unit for the raw materials of its products. To complete each unit incurred $2 per unit in direct labour.

Production overheads for the year based on normal output of 12,000 units was $72,000.

Due to industrial action only 10,000 units were produced and 1,000 units were in inventory at the end of the year.

As a result of the industrial action some units were badly stored and became damaged. It’s is estimated that 200 of the units will now only be sold for $12 each after minor repairs of $2 each

What figure for closing inventory would be shown in the Statement of Financial Position?

Show answerHide answer

$/unit

Material cost

3

Labour cost

2

Overheads

(=72,000/12,000)

6

Total cost

11

NRV = $12 - $2 = $10

Total inventory valuation = (800 undamaged units x $11) + (200 damaged units x $10) = $10,800.

Example 3

A manufacturer is valuing its inventory at the reporting date and has identified the following items to be valued:

Inventory A – work in progress consists of 10 items that have cost $2,500 to produce in total. It is expected that each item will sell for $280, where direct selling costs are expected to be 5% of the selling price, and it is estimated that costs to complete would be $10 per unit.

Inventory B – the company has 1,000 units costing $10 each, where the packaging has been damaged. It will cost $2,000 to repackage all of the units allowing them to be sold at $11 each.

Inventory C – the company has produced inventory costing $7,000 that it is expecting to sell at $10,000 to one of its customers. Changes in production methods mean that the goods are cheaper to produce and will only cost $6,000 in the future.

At what amounts should the inventory be valued in the financial statements.

Show answerHide answer

Inventory A @ $2,500

Cost (lower) = $2,500

NRV = ($280 - $10 – $14 (5% x $280)) x 10 units = $2,560

Inventory B @ $9,000

Cost = 1,000 x $10 = $10,000

NRV (lower) = (1,000 x $11) - $2,000 = $9,000

Inventory C @ $7,000

Cost (lower) = $7,000, ignoring the future costs of production

NRV = $10,000

2 Agriculture (IAS 41)

YouTube video
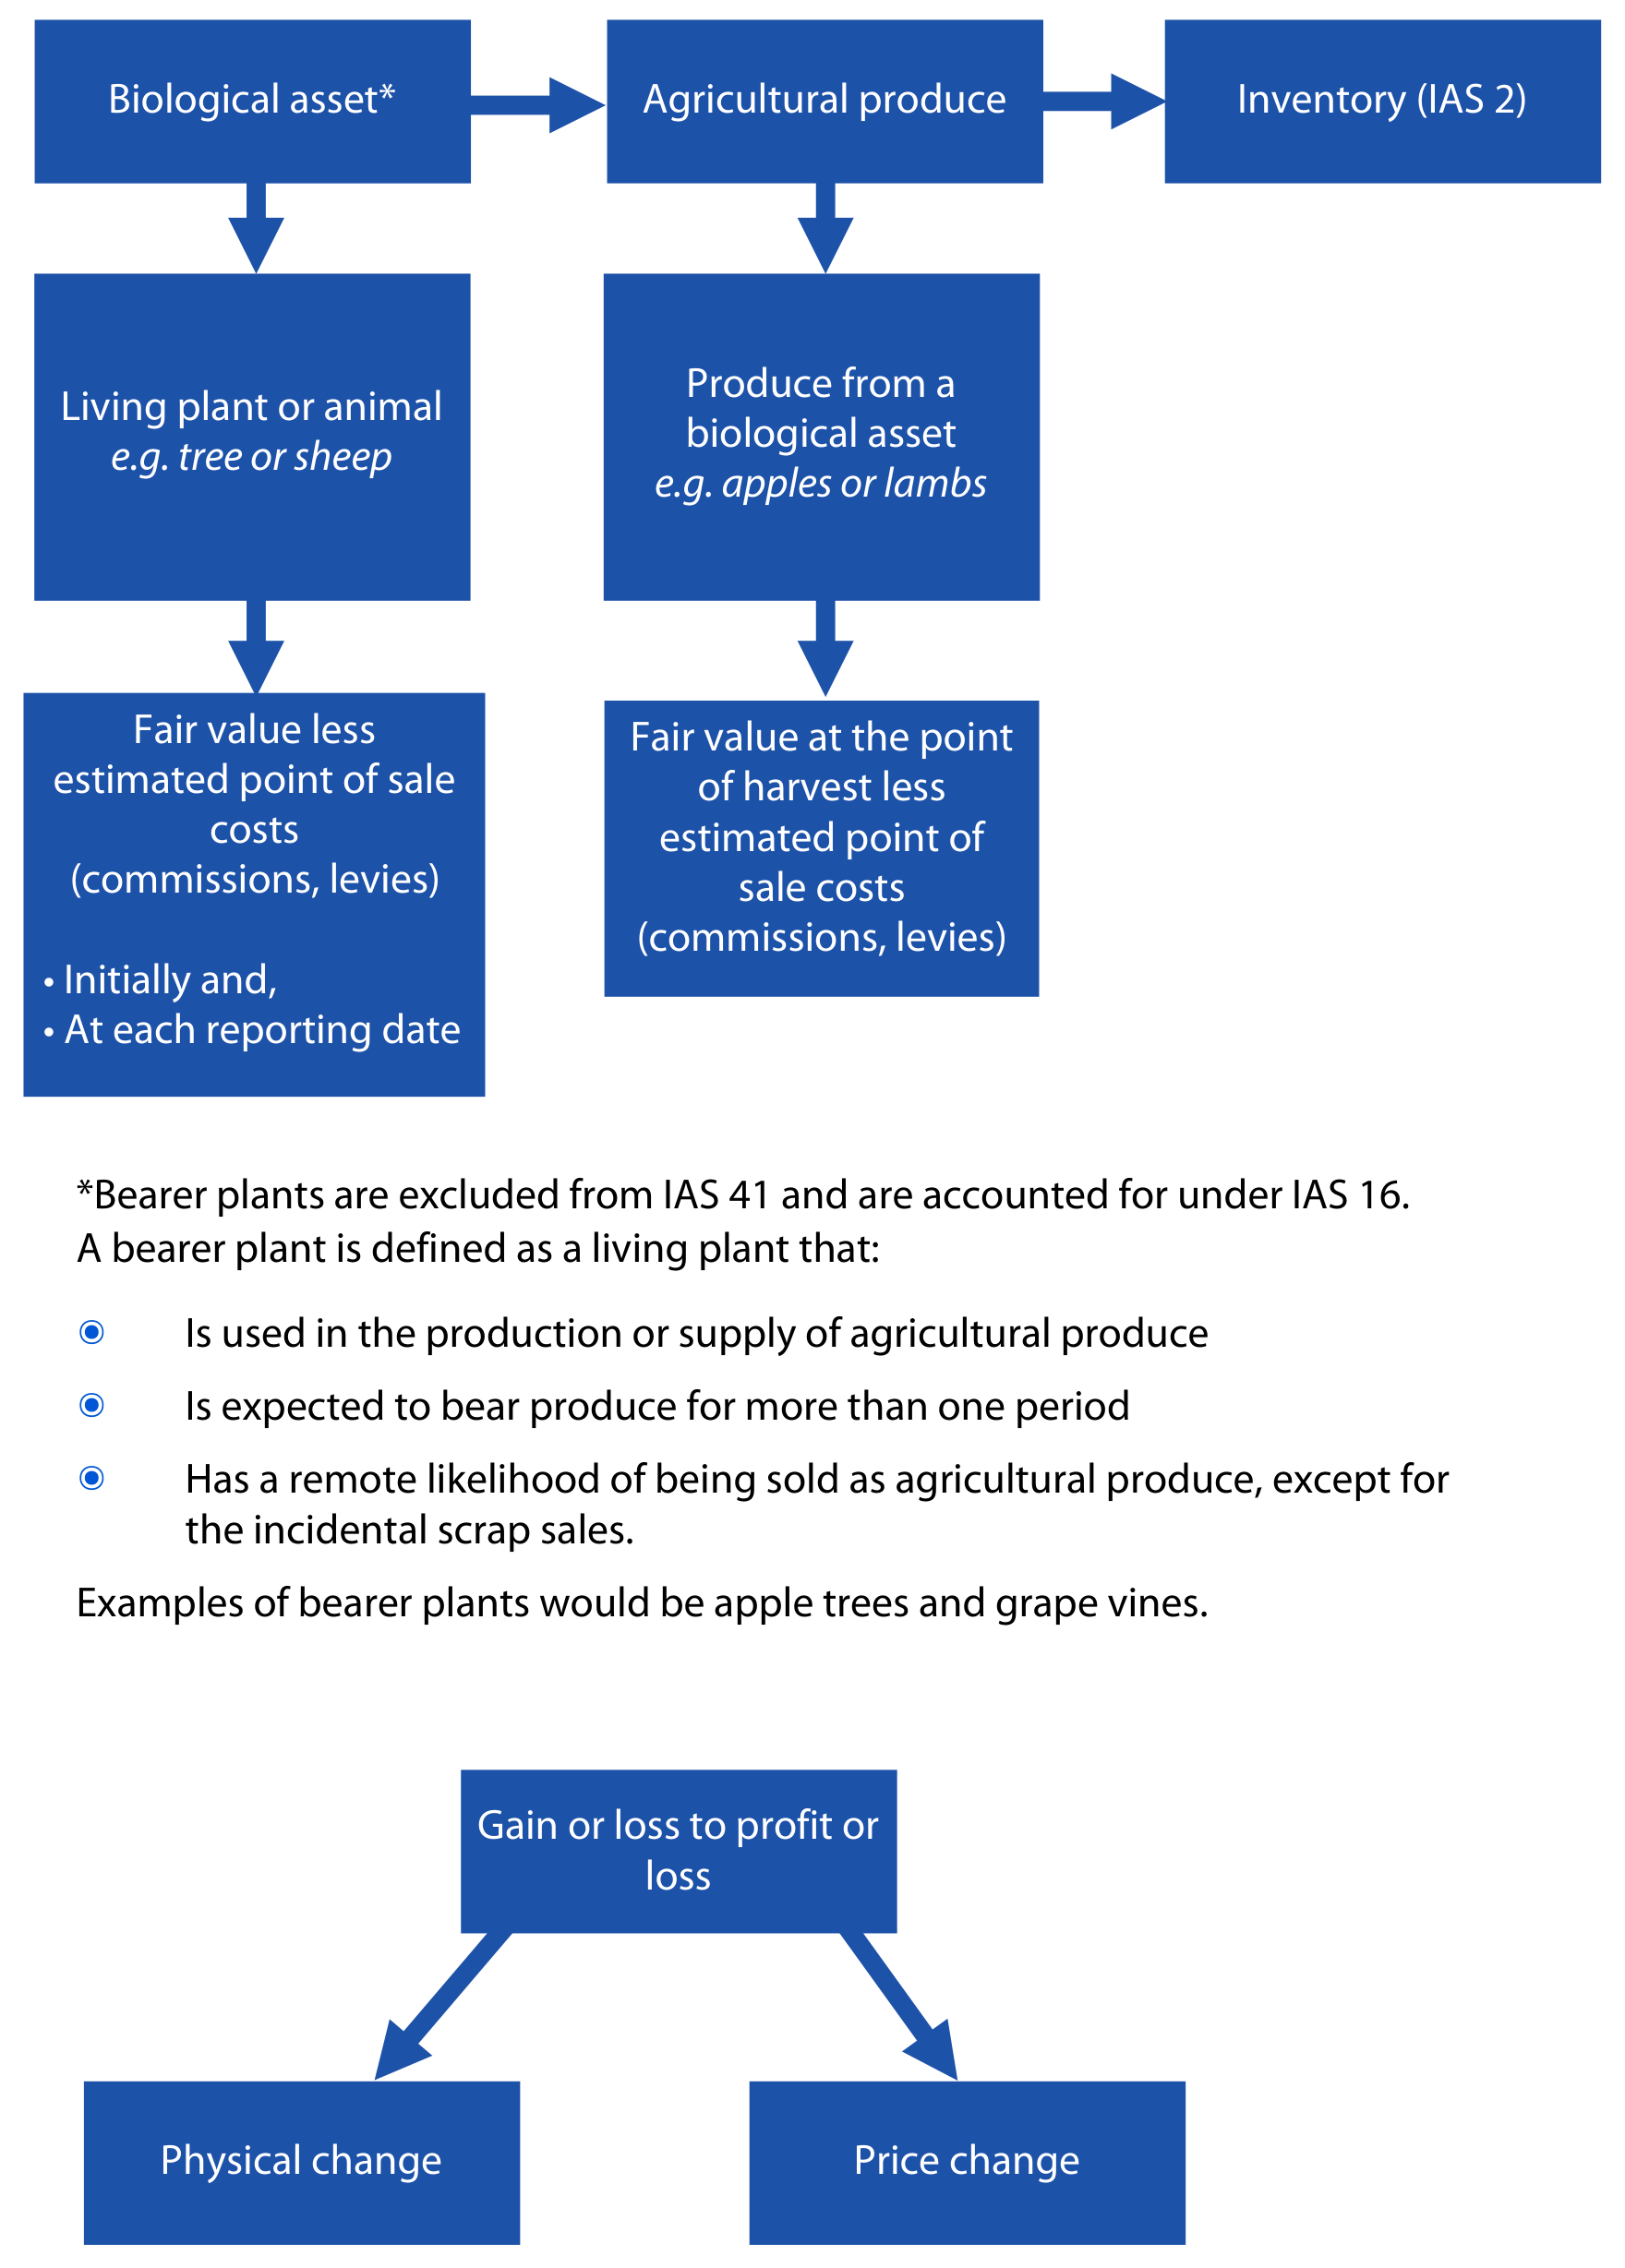
IAS 41: biological asset, agricultural produce and inventory

Note:

  • Agricultural land is accounted for under IAS 16 Property, plant and equipment

  • Milk quotas are accounted for under IAS 38 Intangible assets

  • Grant income for agricultural activity is credited to profit or loss as soon as they are unconditionally receivable.

Practice questions

Inventories (IAS 2)

9 questions

Answer the questions one at a time. Your progress is saved so you can leave and come back.

Open chapter practice