
Depreciation

A non-current asset is used up over several years, so its cost is spread over its useful life as an annual depreciation expense, and its carrying amount in the statement of financial position falls each year. This chapter covers the two methods you must know (straight line and reducing balance), the double entry, the disposal of an asset (with its profit or loss on sale), the revaluation of an asset and the depreciation that follows, and the non-current asset register. Chapter 6 adds what IAS 16 says about cost, revaluation and impairment.
1 Introduction
In this chapter we will explain what depreciation is and why it is needed. We will also look at the different methods of calculating depreciation of which you need to be aware, and the accounting entries.
There are five lectures for this chapter. The first introduces depreciation and the difference between the cost of an asset and its running costs; the other four work Examples 1 to 4 in turn. Revaluation (section 7 and Example 5) is worked in the Chapter 16 lectures on limited companies. The tutor uses older names such as “carrying value”; the current term, used on this page, is carrying amount — they mean the same thing. He also says “pounds” in places where the page uses dollars.
2 Non-current assets
A non-current asset is an asset intended for use on a continuing basis in the business.
A tangible non-current asset is one that can be touched and refers to such items as plant, buildings and motor vehicles.
An intangible non-current asset is one that cannot be touched and refers to such items as goodwill and patents (we will cover these in a later chapter).
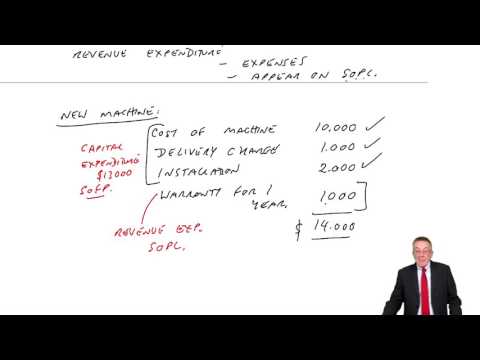
The cost of a non-current asset is everything spent to get it to where it will be used and working — for example the purchase price, delivery and installation. Running costs such as a service contract or repairs are revenue expenditure and are charged as expenses. Chapter 6 sets out the IAS 16 rules.
3 Depreciation
Depreciation is the charging of the cost of a non-current asset over its useful life.
IAS 16 describes depreciation as the systematic allocation of the depreciable amount of an asset over its useful life. The depreciable amount is the cost (or revalued amount) less the residual value — the amount the business expects to get for the asset at the end of its useful life. The useful life is the period over which the business expects to use the asset. Both are estimates.
The purchase of a car for $10,000 is an expense of running the business just as electricity is an expense. However, if the car is expected to last 5 years, it would be misleading to have one expense in the Statement of Profit or Loss of $10,000 every 5 years and nothing in the other years. It would be more sensible to reflect the fact that the car is being used in the business over 5 years by charging an expense each year of (say) $2,000.
The charge of $2,000 in the Statement of Profit or Loss each year is known as depreciation. At the same time, the Statement of Financial Position value of the car will be reduced by $2,000 each year to reflect the fact that it is being used up.
The way in which $2,000 was calculated in the above illustration is known as the straight-line method of depreciation. There are other methods and we will cover the methods that you need to know in the following sections of this chapter.
The purpose of depreciation is not to place a true value on the asset in the Statement of Financial Position. It is a method of applying the accruals, or matching, concept by charging the cost of the asset to the Statement of Profit or Loss as it is being used up.
The cost of the asset less its accumulated depreciation is its carrying amount (older books use other names for it, such as written down value).
4 Methods of calculating depreciation
There are several methods of calculating depreciation. The methods that you are expected to be aware of are the following:
straight line method
reducing balance method
These are the most common methods in practice.
4.1 Straight line method

Under this approach we charge an equal amount of depreciation each year.
The depreciation charge each year is calculated as:
Annual depreciation = (original cost – residual value) ÷ estimated useful life
The rate is sometimes given as a percentage of cost instead: 20% straight line is the same as a five-year life with no residual value. Do not confuse a straight-line percentage (always applied to cost) with a reducing-balance percentage.
Sarkans has a year end of 31 December each year.
On 1 April 2002 he purchases a car for $12,000. The car is expected to last for 5 years and to have a scrap value at the end of 5 years of $2,000.
You are required to calculate the depreciation charge for each of the first three accounting periods, and to show extracts from the Statement of Financial Position and Statement of Profit or Loss for each of the three accounting periods.
Show answerHide answer
(Note, in the first accounting period we have charged a fraction of the annual depreciation because the asset was purchased during the year. A very common alternative in practice is to charge a full year in the year of purchase, regardless of when in the year it was actually purchased. In the examination, read the question carefully. If you are told to charge a full year in the year of purchase then do so. If you are not told, then charge a fraction (or time-apportion) as above.)
4.2 Reducing balance method

Under this approach we charge more depreciation in the early years of an asset’s life, with a progressively lower charge in each subsequent year.
The depreciation charge each year is a fixed percentage of the carrying amount at the end of the previous year.
Annual depreciation = rate % × carrying amount brought forward (cost – accumulated depreciation)
Zils has a year end of 31 December each year.
On 5 April 2002 he purchased a machine for $15,000.
His depreciation policy is to charge 20% reducing balance, with a full year’s charge in the year of purchase.
You are required to calculate the depreciation charge for each of the first three accounting periods, and to show extracts from the Statement of Financial Position and Statement of Profit or Loss for each of the three accounting periods.
Show answerHide answer
5 Accounting for depreciation

Whichever method is used, the accounting entries are the same.
We will illustrate the required entries using an example, and will then summarise the entries afterwards.
Melns has a year end of 30 June each year.
On 1 January 2002 he purchased a car for $15,000.
The car has an expected life of 5 years, with an estimated scrap value of $1,000.
Melns’s depreciation policy is to use straight line depreciation.
Show the accounting entries for the first three accounting periods.
Show answerHide answer
The accounting entry for charging depreciation each year is:
Account | |
Debit | Depreciation Expense account |
Credit | Accumulated Depreciation account |
The balance on the Depreciation Account will appear in the Statement of Profit or Loss as an expense.
The balance on the Accumulated Depreciation account will appear in the Statement of Financial Position as a deduction from the cost of the asset.
6 Sale of non-current assets

In practice it is unlikely that an asset will be kept for the precise useful life that was estimated for depreciation purposes – it might be kept for a longer period or for a shorter period. It is also extremely unlikely that any sale proceeds will exactly equal the value of the asset as shown in the financial statements.
On sale, we remove the asset from our books and calculate any difference between the proceeds and the carrying amount. This difference (which is really the effective over or under charge of depreciation) is called the profit or loss on sale and is shown in the Statement of Profit or Loss.
In Example 3, Melns sells the car on 30 September 2004 for $6,500.
Write up the ledger accounts for his fourth accounting period and show extracts from his Statement of Financial Position and Statement of Profit or Loss.
Show answerHide answer
Note that in this example we have charged depreciation in the year of sale for the 3 months the car was owned. Very often you will be told that the depreciation policy is to charge no depreciation in the year of sale. The net result in the Statement of Profit or Loss will be exactly the same.
Summary of the accounting entries for the sale of a non-current asset:
Entry | Debit | Credit |
With the cost of the asset sold | Disposal account | Asset account |
With the accumulated depreciation on the asset sold | Accumulated depreciation account | Disposal account |
With the proceeds of sale | Cash (or receivables) | Disposal account |
The balance remaining on the Disposal Account is the profit or loss on sale. This should be transferred to the Statement of Profit or Loss.
Part exchange. When an old asset is traded in against a new one, the trade-in (part-exchange) allowance is treated as the sale proceeds of the old asset: Dr New asset account, Cr Disposal account with the allowance. The new asset’s cost is the allowance plus the cash paid. For example, an old machine costing $40,000 with accumulated depreciation of $31,000 (carrying amount $9,000) traded in for an allowance of $12,000 gives a profit on disposal of $3,000.
7 Revaluation of non-current assets
During a period of high inflation, the value of non-current assets may be well in excess of their carrying amount.
In this situation a company may choose to show the current worth of such assets on their Statement of Financial Position.
Any profit resulting from such revaluation is an unrealised profit (in that the asset has not been sold and therefore no real profit has actually been made). As a result, the profit is shown separately from the Statement of Profit or Loss in a revaluation reserve. (For a limited company this must be the case. For a sole trader, where the owner has unlimited liability, this is not a rule even though it is good practice.)
Under IAS 16 the gain on revaluation (the revaluation surplus) is reported as other comprehensive income, not as profit, and is accumulated in equity in a revaluation surplus (revaluation reserve). The entries are: remove the accumulated depreciation to date (Dr Accumulated depreciation, Cr Revaluation surplus), then adjust the asset account from cost to the valuation (Dr or Cr Asset, with the other side to the Revaluation surplus). A fall in value is dealt with in Chapter 6.
IAS 16 Property, Plant and Equipment requires that when an item of property, plant or equipment is revalued, then the entire class of property, plant and equipment to which the asset belongs must be revalued.
When a non-current asset has been revalued, the future charge for depreciation should be based on the revalued amount and the remaining economic life of the asset.
The depreciation charge will then usually be higher than it was before the revaluation. IAS 16 allows (but does not require) the excess of the new charge over the charge based on original cost to be transferred each year from the revaluation surplus to retained earnings (accumulated profits): Dr Revaluation surplus, Cr Retained earnings. This transfer does not go through the statement of profit or loss. It is common practice, and this chapter makes it.
Purpurs has a year end of 31 December each year.
In his Statement of Financial Position as at 31 December 2002 he has buildings at a cost of $3,600,000 and accumulated depreciation of $1,080,000.
His depreciation policy is to charge 2% straight line.
On 30 June 2003, the building is to be revalued at $3,072,000. There is no change in the remaining estimated useful life of the building.
Show the relevant ledger accounts for the year to 31 December 2003.
Show answerHide answer
8 The non-current assets register
In its nominal ledger, a business will typically have accounts for the cost of each class of non-current asset e.g. buildings, plant and machinery. There will also be accounts for the accumulated depreciation for each class of non-current asset.
Every time a new item is bought, its cost will be debited to the appropriate cost account. The cost accounts therefore keep track of the total cost of each type of non-current asset and similarly the accumulated depreciation accounts keep track of the total accumulated depreciation for each type of asset.
However, more detailed information is also required. For example, when an asset is sold its depreciation to date has to be transferred to the disposals account, so records are needed of how much depreciation attaches to each individual asset. Similarly, if we are using straight-line depreciation and an asset is fully written down to a carrying amount of zero, no more depreciation should be applied to it.
The more detailed information needed is recorded in a non-current asset register; this is a memorandum record and is not part of the double-entry system.
The non-current assets register has a page for each non-current asset.
Typically it will list out:
Information | Reason for the information |
Cost | Basic accounting information. Needed for depreciation calculations and on the disposal of the asset. The sum of the costs of the assets should agree to the amount in the cost account in the nominal ledger. |
Date purchased | Might be needed for depreciation calculations or the identification of old assets. |
Accumulated depreciation | Basic accounting information. Needed for depreciation calculations and on the disposal of the asset. The sum of the accumulated depreciation of the assets should agree to the amount in the accumulated depreciation account in the nominal ledger. |
Depreciation method | Needed for depreciation calculations. |
Estimated useful life (or depreciation rate) | Needed for depreciation calculations. |
Estimated residual value | Needed for depreciation calculations if using straight-line depreciation. |
Supplier’s name, address, and the item’s serial number | Needed for maintenance and renewal of assets |
Location of the asset | Needed for physical inspection of the asset or for routine maintenance checks. |
Date asset last inspected | Needed for auditing, maintenance and safety procedures. |
Date asset scrapped or sold | Needed for auditing purposes. |
9 Test your knowledge
Two quick checks before you move on: work through the flashcards to fix this chapter’s terms and definitions, then sit the objective questions for exam-style practice. Both mark themselves and explain the answers as you go.
Depreciation
12 questionsAnswer the questions one at a time. Your progress is saved so you can leave and come back.
Open chapter practice