
Statement of cash flows (IAS 7)

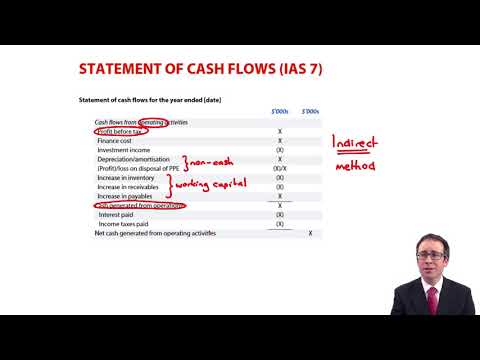
Statements of cash flows are examinable in the ACCA FR exam but only to the extent that you will be required to prepare extracts from the statement of cash flow, and only the indirect method will be examinable.
Statement of cash flows for the year ended [date]

Cash flows from operating activities | $'000s | $'000s |
Operating profit | X | |
Depreciation/amortisation | X | |
(Profit)/loss on disposal of PPE | (X)/X | |
Increase in inventory | (X) | |
Increase in receivables | (X) | |
Increase in payables | X | |
Cash generated from operations | X | |
Income taxes paid | (X) | |
Net cash generated from operating activities | X | |
Cash flows from investing activities | ||
Proceeds from sale of PPE | X | |
Purchase of PPE | (X) | |
Interest received | X | |
Dividends received | X | |
Net cash used in investing activities | (X) | |
Cash flows from financing activities | ||
Proceeds from issue of equity shares | X | |
Repayment of long-term borrowings | (X) | |
Proceeds from issue of long-term borrowings | X | |
Dividend paid | (X) | |
Interest paid | (X) | |
Net cash generated from financing activities | (X) | |
Net increase/(decrease) in cash and cash equivalents | X | |
Cash and cash equivalents at the beginning of the period | X | |
Cash and cash equivalents at the end of the period | X | |
Tax paid
Tax payable | ||||
B/f – current tax | X | |||
– deferred tax | X | |||
Bank (β) | X | Tax expense (SPL) | X | |
C/f – current tax | X | |||
– deferred tax | X | |||
X | X | |||
Property, plant and equipment (PPE)
PPE (CV) | ||||
B/f | X | |||
Depreciation | X | |||
Revaluation | X | |||
Disposal | X | |||
Cash - additions (β) | X | |||
C/f | X | |||
X | X | |||
And,
π/λ on disposal | = | Proceeds | less | Carrying value |
Equity shares
Issue of shares = movement in share capital and share premium
Every figure in the financing section is cash that actually moved in the year, not an expense. Interest paid has its own line in the layout above and is not rolled into the repayment of borrowings, and the amount shown for a repayment is the cash repaid, not the repayment plus the interest charged in profit or loss.
Borrowings
Issue of debt = increase in borrowings
Repayment of debt = decrease in borrowings
Dividend paid
Retained earnings | ||||
B/f | X | |||
Dividend paid (β) | X | Profit (SPL) | X | |
C/f | X | |||
X | X | |||
Interest paid
Interest payable | ||||
B/f | X | |||
Bank (β) | X | Interest expense (SPL) | X | |
C/f | X | |||
X | X | |||
Cash and cash equivalents
B/f | C/f | Movement | ||
|---|---|---|---|---|
Cash | X | X | ||
Cash equivalents | X | X | ||
Overdraft | (X) | (X) | ||
X | X | X/(X) |

Cash flow from operating activities
The following information relates to Geofrost, a limited liability company, for the year ended 31 October 20X7.
Extracts from the statement of profit or loss for the year ended 31 October 20X7
$’000 | |
Interest expense on borrowings and lease liabilities | (400) |
Interest income | 180 |
Profit before income taxes | 15,000 |
Income taxes | (4,350) |
Profit | 10,650 |
Extracts from the Statement of financial position as at 31 October 20X7
20X7 | 20X6 | |
Current assets | ||
Inventory | 3,560 | 9,635 |
Receivables | 6,405 | 4,542 |
Cash | 2,045 | 1,063 |
12,010 | 15,240 | |
Current liabilities | ||
Bank overdraft | 1,230 | 429 |
Trade payables | 7,562 | 4,364 |
Tax payable | 3,020 | 2,760 |
11,812 | 7,553 |
Additional information:
Depreciation expense for the year was $4,658,000
Assets with a carrying value of $1,974,000 were disposed of at a profit of $720,000
Prepare the cash generated from operating activities section from the statement of cash flows.
Show answerHide answer
Cash flow from investing and financing activities
The following information relates to Geofrost, a limited liability company, for the year ended 31 October 20X7.
Extracts from the statement of profit or loss for the year ended 31 October 20X7
$’000 | |
Interest expense on borrowings and lease liabilities | (400) |
Interest income | 180 |
Profit before income taxes | 15,000 |
Income taxes | (4,350) |
Profit | 10,650 |
Extracts from the Statement of financial position as at 31 October 20X7
20X7 | 20X6 | ||
Assets | |||
Non-current assets | 43,282 | 26,574 | |
Equity and liabilities | |||
Capital and liabilities | |||
Equity share capital | 19,365 | 17,496 | |
Retained earnings | 16,115 | 6,465 | |
35,480 | 23,961 | ||
Non-current liabilities | |||
Loan | 8,000 | 10,300 |
Additional information:
Depreciation expense for the year was $4,658,000
Assets with a carrying value of $1,974,000 were disposed of at a profit of $720,000
Prepare the following extracts from the statement of cash flows:
- Cash flow generated from investing activities
- Cash flow generated from financing activities
Show answerHide answer
Statement of cash flows (IAS 7)
10 questionsAnswer the questions one at a time. Your progress is saved so you can leave and come back.
Open chapter practice