
Foreign currency (IAS 21)

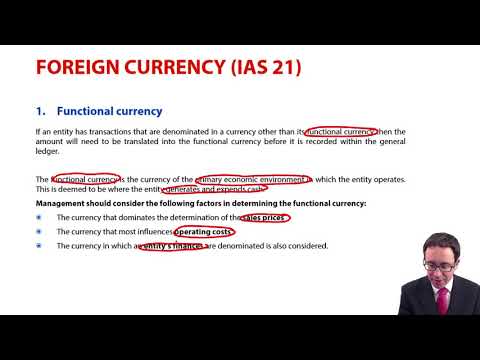
1 Functional currency
If an entity has transactions that are denominated in a currency other than its functional currency then the amount will need to be translated into the functional currency before it is recorded within the general ledger.
The functional currency is the currency of the primary economic environment in which the entity operates. This is deemed to be where the entity generates and expends cash.
Management should consider the following factors in determining the functional currency:
The currency that dominates the determination of the sales prices
The currency that most influences operating costs
The currency in which an entity’s finances are denominated is also considered.
2 Recognition and measurement
Record the transaction at the exchange rate in place on the date the transaction occurs (historic rate – HR).
Monetary assets and liabilities are retranslated using the closing rate (CR) at the reporting date, with any gains or losses going through profit or loss.
Non-monetary assets and liabilities are not retranslated at the reporting date, unless carried at fair value, whereby translate at the rate when fair value was established.
Note: No specific guidance is given as to where any exchange differences are recorded within profit or loss. The general accepted practice is:
Trading transaction – operating costs
Financing transaction – financing costs
Settle three things in order before touching the numbers: whether the balance is monetary, which it must be for any retranslation at all; which way the rate has moved, since a difference can as easily be a gain as a loss; and which line it belongs on, operating for a trading balance and finance for a borrowing. A retranslation gain increases profit, so any margin or return calculated after the adjustment moves with it.

Functional currency (1)
Jones Inc. has its functional currency as the $USD.
It trades with several suppliers overseas and bought goods costing 400,000 Dinar on 1 December 2017. Jones paid for the goods on 10 January 2018. Jones’s year-end is 31 December.
The exchange rates were as follows:
1 December 2017 | 4.1 Dinar : $1USD |
31 December 2017 | 4.3 Dinar : $1USD |
10 January 2018 | 4.4 Dinar : $1USD |
Show how the transaction would be recorded in Jones’s financial statements.
Show answerHide answer
Foreign currency transactions (IAS 21)
10 questionsAnswer the questions one at a time. Your progress is saved so you can leave and come back.
Open chapter practice