
Events after the reporting date (IAS 10)


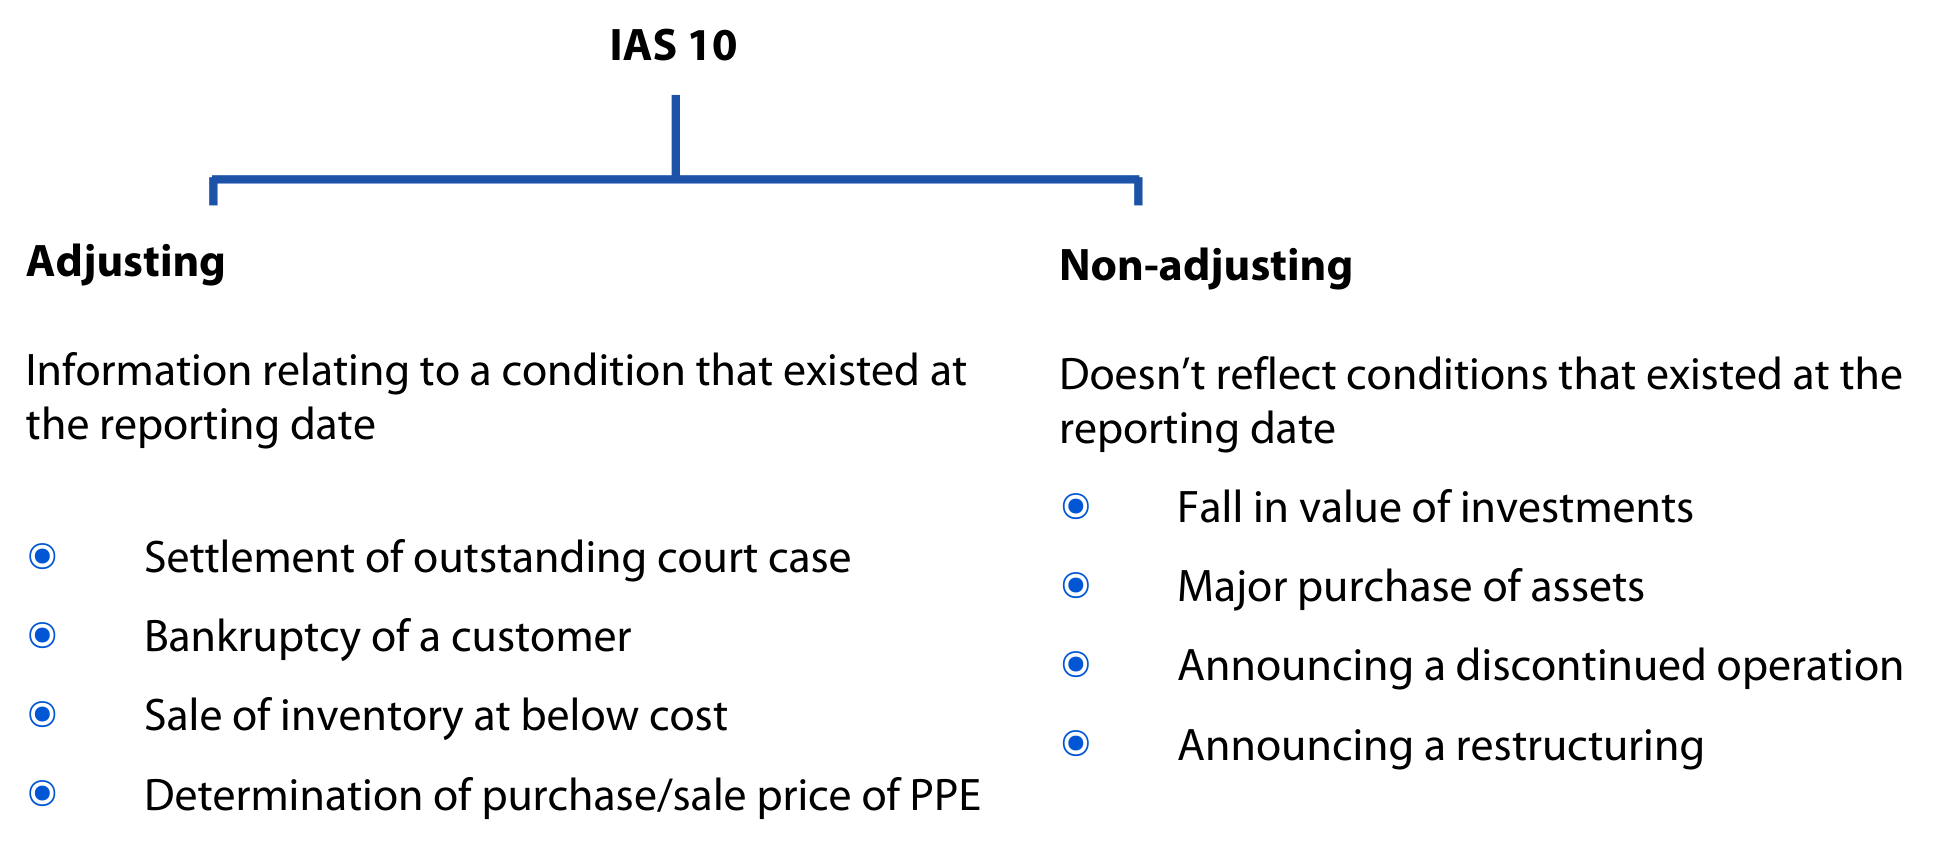
The following material events occurred after the reporting date but before the financial statements were authorised for issue:
1. A later valuation provides evidence that a property was impaired at the reporting date.
2. Inventory held at the reporting date is sold soon afterwards under normal market conditions for less than cost, confirming its year-end net realisable value.
3. Fraud or an error is discovered that affected the financial statements for the year just ended.
4. A customer owing money at the reporting date becomes insolvent, confirming that the receivable was credit-impaired at year end.
Which events are adjusting events under IAS 10?
Example 2 – Events after the reporting period
The following events took place between the 31 December 2017 reporting date and the date the financial statements were authorised for issue.
The company makes an issue of 100,000 shares which raises $200,000 shortly after the Statement of Financial Position date.
A legal action had been brought against the company for breach of contract prior to the year end. The outcome was decided shortly after the Statement of Financial Position date, and as a result the company will have to pay costs and damages totalling $80,000. No provision has currently been made for this event.
Inventory included in the accounts at the year end at cost $25,000 was subsequently sold for $15,000.
A building in use at the Statement of Financial Position date and valued at $500,000 was completely destroyed by fire. Unfortunately, only half of the value was covered by insurance
Which of the above events are adjusting events in the financial statements.
Show answerHide answer
Non-adjusting events as the issue of shares does not give evidence of a condition that existed at the year-end. The company would use the issue of shares in its calculation of basic EPS.
An adjusting event as the legal action and its outcome give evidence of a condition the existed at the reporting date. A provision of $80,000 would be made.
An adjusting event that reduces the value of year-end inventory by $10,000 as it gives evidence of the fall in value of the inventory held at the reporting date. Inventory included in the accounts at the year-end would now be included at $15,000.
A non-adjusting event as the condition did not exist at the reporting date. As the item is material a disclosure of its nature and financial impact would be made in the notes.
Events after the reporting period (IAS 10)
10 questionsAnswer the questions one at a time. Your progress is saved so you can leave and come back.
Open chapter practice