
Corporate Governance and Auditor Regulation


1 Why corporate governance is needed
Corporate governance is the system by which companies are directed and controlled. Auditing financial statements adds to their credibility and this enables shareholders to better understand how the directors and company have performed.
2 Principles of corporate governance
The Organisation of Economic Cooperation Development (OECD) promotes six Principles of a corporate governance framework:
It should promote transparent and fair markets and the efficient allocation of resources and support effective supervision and enforcement.
It should protect shareholders’ rights, ensuring fair treatment of all shareholders, including minority and foreign shareholders. For example all shareholders should have access to the same information.
It should provide for stock markets to function in a way that contributes to good corporate governance (eg insider trading should be prohibited).
It should recognise the rights of all stakeholders, not just shareholders, and encourage active cooperation between the entities and stakeholders in creating wealth, jobs and sustainability of financially sound entities.
It should ensure timely and accurate disclosure on all material matters, including financial position, performance, ownership and governance.
It should ensure the strategic guidance of the entity, effective monitoring of management by the board and the board’s accountability to the entity and their shareholders. In particular the board should set its own objectives, monitor its own performance and have its own performance assessed.
3 The UK Corporate Governance Code
The OECD principles are put into effect in a variety of ways in different countries. The UK Corporate Governance Code published by the Financial Reporting Council (FRC) can be referred to as an example of best practice.
The Principles of the Code emphasise the value of good corporate governance to the long-term success of the company.
Comply or explain
The Code has no force in law and is enforced on listed companies through the Stock Exchange. Listed companies are expected to ‘‘comply or explain’’ and this approach is the trademark of corporate governance in the UK.
Listed companies have to state that they have complied with the code or else explain to shareholders why they haven’t. This allows some flexibility and non-compliance might be acceptable in some circumstances.
The UK and most of Europe have adopted a principles-based approach rather than a rules-based approach to Corporate Governance. Broad principles are set out but then companies decide how to put those into operation. This can provide flexibility and adaptability.
In the US most corporate governance is regulated through statute, the Sarbanes-Oxley Act 2002. This takes a procedural ('rules-based') approach that is much more prescriptive, requiring both directors and auditors to sign off documentation stating that the rules have been followed. Criminal charges can follow if the Act is not followed.
Main principles of the UK Code
Board Leadership and Company Purpose
Division of Responsibilities
Composition, Succession and Evaluation
Audit, Risk and Internal Control
Remuneration
Board Leadership and Company Purpose
Every company should be headed by an effective board which is collectively responsible for the long-term success of the company.
All directors must act with integrity, lead by example and promote the desired culture.
The board should:
establish the company’s purpose, values and strategy
ensure the company has the necessary resources to meet its objectives
establish effective controls to assess and manage risk
ensure effective engagement with, and encourage participation from, stakeholders
ensure that workforce policies and practices are consistent with the company’s values and support its long-term success.
Division of Responsibilities
There should be a clear division… between the running of the board and the executive responsibility for the running of the company’s business. No one individual should dominate decision making. This means that the roles of CEO and chair should not be performed by one person as that concentrates too much power in that person.
The chair is responsible for leadership of the board and should be independent on appointment (e.g. not an employee within the last 5 years).
At least half the board should be non-executive directors (NEDs) who are considered independent (e.g. no close family ties with executive directors, no significant shareholdings, etc).
NEDs should provide constructive challenge and strategic guidance and hold management to account.
Composition, Succession and Evaluation
Appointments to the board should be subject to a formal, rigorous and transparent procedure led by a nomination committee. A majority of the committee should be independent NEDs.
The board and its committees should have a combination of skills, experience and knowledge. The length of service of the board as a whole should be considered and membership regularly refreshed. The post of chairman should not be held beyond nine years.
The board should undertake a formal and rigorous annual evaluation of its own performance and that of its committees and individual directors.
All directors should be submitted for re-election annually.
Audit, Risk and Internal Control
The board should establish formal and transparent policies and procedures to ensure the independence and effectiveness of internal and external audit and the integrity of financial statements.
The board should present a fair, balanced and understandable assessment of the company’s position and prospects. The financial statements should state whether the board considered the appropriateness of the going concern basis of accounting and identify any material uncertainties for at least 12 months from the date of approval of the financial statements.
The board should establish procedures to manage risk, oversee internal controls and determine the nature and extent of the principal risks the company is willing to take to achieve its long-term strategic objectives.
To meet the above Principles, the board should establish an audit committee of at least three independent NEDs (two for smaller companies). At least one committee member must have recent and relevant financial experience.
Remuneration
In essence, remuneration should be sufficient to attract, retain and motivate directors of sufficient quality… but avoid paying more than is necessary.
Remuneration policies and practices should be designed to support strategy and promote long-term sustainable success. For example, a significant proportion of executive directors’ remuneration may be structured to link rewards to corporate and individual performance. In other words, profit-related pay is encouraged. Directors should not receive high pay irrespective of company performance.
There should be a formal and transparent procedure for developing policy on executive remuneration and for fixing the remuneration packages of individual directors. No director should be involved in deciding his or her own remuneration. This means that a remuneration committee (NEDs) should be formed to fix directors’ remuneration.
4 The role of the audit committee
The audit committee is a very important part of corporate governance.
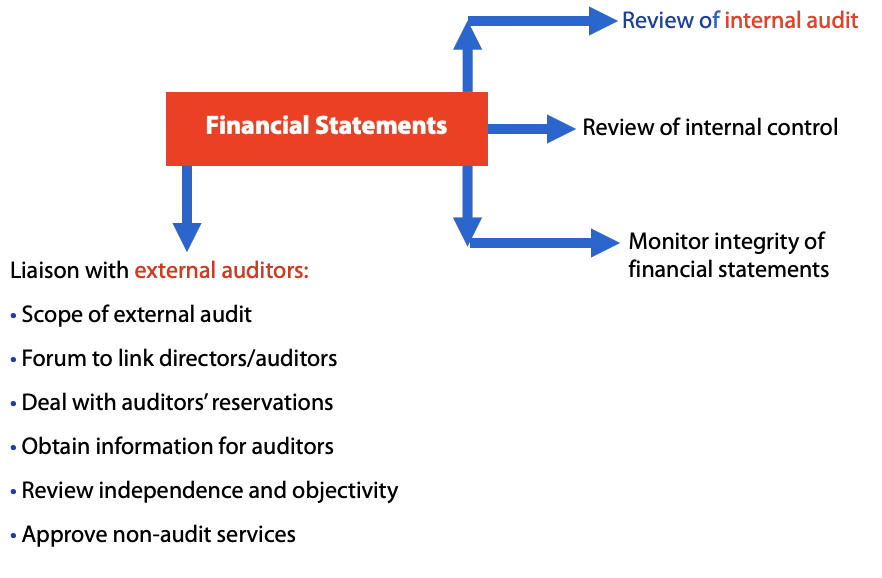
The main roles and responsibilities of the audit committee include the following:
Monitoring and reviewing the effectiveness of internal audit. Companies don’t have to have an internal audit department, but the need for one must be reviewed annually.
Monitoring the integrity of the financial statements and reviewing significant financial reporting judgements.
Review the internal financial controls and risk management systems (unless there is a separate risk committee or the board does this).
Making recommendations to the board about the appointment, reappointment and removal of the external auditors and agreeing the terms of engagement. (Note that the external auditors are appointed by members in general meeting, but the board puts forward the nomination.)
Annually assessing the independence, objectivity and effectiveness the external auditors including confirming that there are no self-interest or familiarity issues and that partners and staff are rotated properly.
Acting as a forum to link directors and auditors. Auditors will typically write to the audit committee about any problems they may be having on the audit or obtaining all the information they require. If the auditors are worried in some way about the financial statements they will raise those concerns with the audit committee.
Developing and implementing policy on the engagement of the external auditor to supply non-audit services: skills, approval and non-approval for certain services, ensuring any threats to independence and objectivity are reduced to acceptable levels and monitoring the fees for those services and the total fee for all services provided by the external auditor.
5 Regulation of auditors
Auditors are regulated by:
Professional bodies (eg ACCA). ACCA is a recognised supervisory body that supervises qualifications, behaviour and quality.
National bodies. In the UK and Ireland, the Financial Reporting Council. This regulates auditors and accountants and sets the UK’s Corporate Governance Code.
International bodies (eg IFAC, the International Federation of Accountants). The purpose of IFAC is to serve the public interest by, establishing and promoting adherence to high-quality professional standards.
IFAC has a number of boards and committees such as:
IAASB (International Auditing and Assurance Standards Board): Sets International Standards on Auditing (ISAs) and other assurance standards
IESBA (International Ethics Standards Board for Accountants): Issues the International Code of Ethics for Professional Accountants.
TAC (Transnational Auditors Committee): Responsible for implementing and advancing the promotion of high-quality standards of financial reporting and auditing practices worldwide.
The Public Interest Oversight Board (PIOB) oversees the public interest activities of the standard setters. It brings greater transparency and integrity to the audit profession, thereby contributing to the enhanced quality of international financial reporting.
IAASB's ISAs are adopted by the FRC in the UK which has local regulatory power. The IESBA's Code has been adopted by ACCA in its Code of Ethics and Conduct.