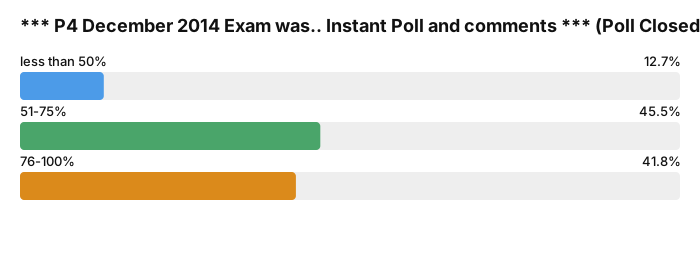Skip to contentSkip to search

ACCA Forums

AFM*** P4 December 2014 Exam was.. Instant Poll and comments ***

Oopentuition_teamAdmin11y ago

Please vote in our Instant Polls about the P4 December 2014 Exam.
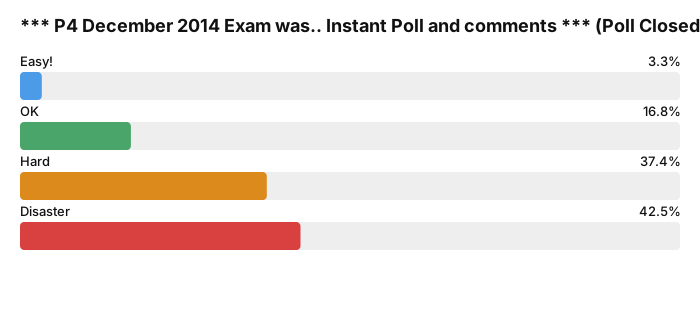
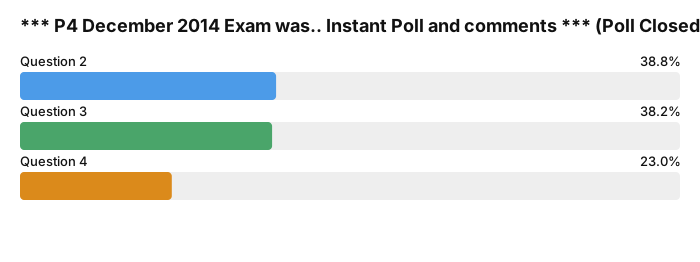
*** P4 December 2014 Exam was.. Instant Poll and comments *** poll results *** P4 December 2014 Exam was.. Instant Poll and comments *** poll results *** P4 December 2014 Exam was.. Instant Poll and comments *** poll results Please note, the ACCA have asked us to allow posting comments only after 5pm UK time.
Former userFormer user11y ago#61
I am taking P5 too, now.... Hope to be better than q4. The MV for debt was indeed 102.4 something
Former userFormer user11y ago#62
@williams1977 I got the same too
FFelix11y ago#63
@williams1977 said: Can someone please clarify in Q1 the question said something like "the share price is $7.5 which is a multiple of 7.2" and they hope earnings will be a multiple of 7.5? Was this just a red herring, false information there to mislead us
this is what I do, $7.5 is meant for us to get the MV of Nahara Co. and then 7.2 is the FCFE multiple, meaning FCFE x this multiple should equal to MV of Nahara Co. Hence, we got the FCFE. Then the question said that the combined multiple will be 7.5. Meaning that, (FCFE of Nahara Co + FCFE of Fugae co + synergy) x multiple = MV of the new combined company. To get the additional value. MV of the combined company - MV of Nahara Co originally - MV of Fugae Co (however I used 1.3x Fugae co MV instead, as this is what Acem co were requested to pay). CMIW
TToyosi11y ago#64
@ kamdarvivek, like I said I "assumed" as there was no time to think at all in that exam. My goal was to do as much as I could within the allotted time. I never completed the put option because I was already getting a negative figure for the call option so I abandoned it....So yes, your logic might be right and you might get the marks.
EEyelash11y ago#65
I genuinely thought i had been studying from incorrect syllabus material as that q1 was simply soul destroying! It was a mess of information and the question didnt even guide you to what the examiner is thinking. With aa lot of past papers, the q1 material seemed a lot more structured dont you think?
EEyelash11y ago#66
Q1 was like the whole syllabus and then some... My heart sank! Didnt know where to start let alone come to any conclusions! this is my final paper and i hadnt failed one to date... Really gutted as wanted this wrapped up :(
Iicedawn11y ago#67
i multiplied the 7.2 to the market price of the share then divided by ke
Former userFormer user11y ago#68
@williams1977 said: Can someone please clarify in Q1 the question said something like "the share price is $7.5 which is a multiple of 7.2" and they hope earnings will be a multiple of 7.5? Was this just a red herring, false information there to mislead us
If you see his previous papers he hardly gives info which is not needed like other examiners. So I wasted sometime on this. At first I thought it could be bootstrapping, then confused it with VCQ, so left it alone.
Former userFormer user11y ago#69
Hi. Does anyone know how futures were to use in Q2. Since the firm was a borrower I used put options to hedge against the risk. but not sure how futures prices come in to play. I used march at 22 basis points.
Wwilliams197711y ago#70
@felixt said: this is what I do, $7.5 is meant for us to get the MV of Nahara Co. and then 7.2 is the FCFE multiple, meaning FCFE x this multiple should equal to MV of Nahara Co. Hence, we got the FCFE. Then the question said that the combined multiple will be 7.5. Meaning that, (FCFE of Nahara Co + FCFE of Fugae co + synergy) x multiple = MV of the new combined company. To get the additional value. MV of the combined company - MV of Nahara Co originally - MV of Fugae Co (however I used 1.3x Fugae co MV instead, as this is what Acem co were requested to pay). CMIW
but in the above you have not used gordons growth model, and it sounds like a lot of people used that way to calculate the MV of Fugae co
Former userFormer user11y ago#71
hi i think that $7.5 was to multiply by no. of shares to get market value of A co and then divide the market value by 7.2 to get FCFE multiplied by growth rate and divide by Ke to get the Ve for A Co.
Former userFormer user11y ago#72
Hey Folks. Just going through what I did Q 1 (a) (b) Theory I think it was about Diverstification of the Company and also buying undervalued companys....write a bit on that and have a decent argument it should not be to bad to get some marks. The other part was about Selling the business if they were going to purchase another company in the same country. I think you mentioned on competitivness, Competition and Monopoly power you would have been generally okay. Again all depends on the discussion. C (i) What a disaster spent about 25 mins and to be honest my answer barely half a page, just used the Ratio think it was 7.5 to calculate the company of the combined company. I took that the say 800 share capital at 50 cent was 1600 shares for example. I made a whole load of other calcs to get growth and dividend growth model of Farage was it? but they were talking about it from Neons point of view and gave enough information to base it off that. Calculated all sorts of stuff just desperately trying to get something that will stick to get some marks. (ii) So I ungeared, then regeared based of the companys equity. I also then used the new beta to calculate the Capm to get the Ke, I then made the assumption that you needed to use this to calculate the value of the cash flows. I did 3 seperate cash flows for the 3 different scenarios and then weighted them based on 20% probability to get the cash flow. Once that was done I noticed for 18 marks there has to be something tricky. I realised it was a put option as they would be abandoning the project for the 50 million. I calculated the value of a call option which was negative and then used the call option in the Put Call Parity formula to get the value of the Putt. Which added value for me. Now all this was very rushed etc and mistakes were made in the caluation of the Beta, but there simply wasnt time to calc and then have a think about it. Approach hopefully gets marks. (iii) Just waffled on, said the acquiree it was not worthwhile but for the acquirer it was. Pure waffle ran out of time. 3 (a) Theory can't remember exactly but didn't seem to difficult. Was it to do with Free Trade?..... (B) IRR, MIRR and VAR was okay....the 90% was a strange we are obviously never given a value but once we knew that the standard deviation and the time was the same you could assume that the the other value of the other company matched the 90% value. Sneaky sneaky question right there. Explain VAR and then recommend which project. I went for the highest NPV as normal as it the best valuation method. (C) Legal risk of working in a different country. Again just used my brain and tried to backup as best I could. 4 (a) What is EVA and explain the advantages and Disadvantages.....tough to get a full 6 marks out of this, you needed to flesh out everything like how useful it is for comparing between different years. (b) Calculate EVA , straightforward (C) Evaluate, I did ratios under liquidity, Investor, Turnover and Gearing. I agreed with the analyst that the company was not that well suited. Massive increase in gearing couple that with increased interest costs also and PE ratio lagging behind industry etc. Was straight forward enough that part but again its all interpretation. Overall I felt C of Question 1 was brutally tough that really was there to expose the student. The real option part maybe the difference between a 33% pass rate and a 40% pass rate. I did both Q3 and Q4 first, I hope my marker see's that I did some decent(not great tbh) work there and gives me enough that when he reads Q1 they have already decided if I pass or fail. Won't hold my breath but Jeez that was tricky. Time again a issue, just finished. Sounds like they may struggle to get people over the line in this exam, Q1 c may be marked very easy as a result.
FFelix11y ago#73
@williams1977 said: but in the above you have not used gordons growth model, and it sounds like a lot of people used that way to calculate the MV of Fugae co
I did, to derive the mv of fugae I used ggm + debt value. I just realised, i should have not add debt.
Eesoluyemo11y ago#74
Key differences are: Salam Contract i) Not standardised ii) Not traded on Exchange iii) Risk of default very high iv) It is an over-the-counter transaction
Former userFormer user11y ago#75
@humzaacca said: hi i think that $7.5 was to multiply by no. of shares to get market value of A co and then divide the market value by 7.2 to get FCFE multiplied by growth rate and divide by Ke to get the Ve for A Co.
I think Felix is right, it's like bootstrapping. Use Gordon growth to calculate g, which u use along with ke n FCFE to get MVe of Fugue alone. Use the multiple to calculate the market value of the combined company.
Mmujji11y ago#76
really was there blackscholes in question 1? i did not notice? which part was it?
Mmujji11y ago#77
@muneebnawaz90 said: Cant we be unethical for a while to say few words for this p4 examiner? Such scattered info in q1 and asked for every single thing in question 1 from blackscholes to wacc and valuation to benefits.
really was there blackscholes in question 1? which part? i did not notice?
Mmujji11y ago#78
@williams1977 said: I calculated market value of debt to be $102 (plus some cents) did anyone get the same?
yup i also got 102 mv debt
Former userFormer user11y ago#79
There was an option to sell the luxury-project end of year two for $50m. Option to abandon. However, I could not find std dev. to use.
Former userFormer user11y ago#80
$102 and come cents aswell
Aasiunial8211y ago#81
Absolutely agree, I cannot believe that I have been studying so much and covered so many topics and then didn't know where to start from (Q1)
Mmujji11y ago#82
yes standard deviation was not given
Aamirali9211y ago#83
At one moment, I kept on shooting the examiner 1000 times in my head looking at the requirements of Qn 1. That was a devastating and horrendous question! I attempted Qn. 3 and 4. and they were that bad (Qn. 4 being a pretty cool question), but those 2 aren't enough to pass the exams. :/
Former userFormer user11y ago#84
Hi, Certainly true. Question # 1 was a mess. I agree that someone saying that at every attempt question 1 is becoming tougher and tougher. Even I don't understand that what is examiner's expectation? There should be some cap on the difficulty level from ACCA. If the examiner is expecting that we are super humans and can understand such complex and comprehensive questions. I don't think that any board or any institution has such typical exam settings. Is any there body or any representative of students to ACCA? I am not sure if opentuition forwards our requests or concerns to ACCA. I think that there should be someone representing students matters, specially these kinds of issues. People are preparing like hell by giving up everything they love to have to pass the exam to have good career but in the exam center they face disaster. Imagine their situation. I saw students sitting next to me were just waiting to get the exam over to go back home as they cannot leave the exam hall until the exam is over. I managed to attempt 65 to 70 percent. Reading time 15 minutes goes like a minute. Reading this kind of question # 1 need at least half an hour to understand only and another hour to solve it. Good luck to those have 50-50 hopes and those who lost hopes, try again, never give up. God bless you all.
Eesoluyemo11y ago#85
I want to believe that the examiner seems to be happy if they are saying that is paper is tough. I beg, ACCA should bring back the former examiner. That one has human feelings that this new one. Since he assumed the post, his questions especially question one are no go area. If truly they are training us what we will be doing in practice, I do not think that we will be facing this kind of problem where information will be made complex as this apart from the fact that we will not be under time constraint like this to solve practical issues in real life. Wicked Examiner! He must have failed many times before he qualified. So, he want to make us to suffer the same faith. Your days are numbered
Former userFormer user11y ago#86
Hi, all of us must have noticed that almost all of us are crying........... How about all of us write to ACCA about the difficulty level of question #1 and request all of us to do the needful.? Imagine if ACCA receiving 100 of mails about question one...... i think the president of ACCA would atleast think to do somethink.
Former userFormer user11y ago#87
100% agreed. Sitting P4 felt like attempting a job screening test with a limited amount of time trying to meet the highest expectations. Tactic was crucial for today's exam. I started with Q 2 without even looking at Q 1. Then tried to attempt as much as possible in Pt c of Q 1 keeping in mind that there were 4 valuable marks for report format. And then attempted the rest of the question. I managed to write solutions to all the parts of all 3 questions including Q 3. Really hope for a favorable result.
Mmaples12311y ago#88
very bad paper this time....the examiner tripped us off in almost all questions...i really wanted to cry:(((((((
Aangelkay11y ago#89
I felt like I was fighting a world war! My head went completely blank after reading Q1, I can still feel that headache. Now I feel like it was a waste taking time off from work to do all this studying. Worked hard and it doesn't seem to be paying off...sometimes it easier to be a bum! I feel like giving up but I know its not in me to give up.
EEyelash11y ago#90
Q1 felt like a maze to actually try and fish out what the examiner was looking for. Can anyone remember the mark-split for q1 ie how many for a, b, c sections
Topic lockedNew replies are closed.