
Tax Adjusted Trading Profit – Individuals


1 Badges of Trade
The following tests are used to establish if a transaction(s) should be treated as trading and taxed as income and therefore subject to Income Tax and Class 4 NIC, or whether they should be treated as capital transactions and treated as capital gains and therefore subject to Capital Gains Tax.
You can use the mnemonic SOFIRM to help you remember the tests, which are known as 'The Badges of Trade'.
1.1 Subject matter
Whether a person is trading or not may sometimes be decided by looking at the subject matter of the transaction.
1.2 Length of ownership
Where items purchased are sold soon afterwards, the transactions are likely to be treated as a trade. If acquired unintentionally (e.g. by inheritance) and then sold, it is unlikely that trading has taken place.
1.3 Frequency of transactions
Transactions of a capital nature will be interpreted as trading transactions where their frequency indicates the carrying on of a trade.
1.4 Supplementary work and marketing: Improvement
When work is done to make an item more marketable, or attempts are made to find purchasers, the transactions are more likely to be treated as a trade.
1.5 Reason for sale
The circumstances/reason for the sale (being forced to make a sale to raise cash may indicate not trading).
1.6 Profit motive
The presence of a profit motive will be a strong indication that a person is trading.
2 Taxable trading profits for unincorporated businesses

From 2024/25, unincorporated businesses (sole traders/partnerships) calculate their taxable trading profit under the CASH BASIS.
Under the cash basis:
1. Include cash received and cash paid (i.e. no accruals) during the accounting period.
2. Cash received and cash paid includes not only cash received from customers/paid to suppliers, but also cash received/paid on the sale/purchase of capital assets that would normally qualify as plant and machinery for capital allowances purposes (see later) with the exception of cars.
3. Capital allowances and running costs, or the fixed rate mileage allowance (see later) can be claimed on cars.
Unincorporated businesses can elect to use the ACCRUALS BASIS in which case capital allowances can be claimed on all capital assets (including cars) that qualify as plant and machinery. If the question is silent, assume that the CASH BASIS is being used.
COMPANIES must use the ACCRUALS BASIS.
3 Adjusting the accounting profit
3.1 Introduction
The tax adjusted trading profit for inclusion within the income tax computation is not the same as the profit shown in the statement of profit or loss.
Accounting profits, or net profit before tax, may have to be adjusted to arrive at tax adjusted trading profit. The main adjustments are to disallow for tax certain non-allowable expenses debited in the accounts and to exclude any non-trading income credited in the accounts.
The proforma used to calculate tax adjusted trading profits is as follows:
£ | |||
Net profit per accounts | X | ||
ADD BACK: Disallowable expenditure* | X | ||
X | |||
LESS: income not assessed as trading profit: | |||
- Income assessable elsewhere (e.g. property income, interest income) | X | ||
- Non-taxable (exempt) income | X | ||
(X) | |||
Adjusted profits before capital allowances | X | ||
LESS: Capital allowances (P&M and SBAs) | (X) | ||
Tax adjusted trading profit | X |
Note:
When preparing this calculation, be careful to start with the NET profit per accounts.
READ THE QUESTION CAREFULLY!
It is important to understand that the object of the exercise is to isolate the profit that purely relates to the business's TRADING activities.
*Just because an expense is disallowed at this point does not mean that the expense is not tax deductible. For example, it may be deductible as a property expense.
3.2 Typical expenditure by a business
The general rule is that expenditure not wholly and exclusively for the purpose of the TRADE is not allowable.
READ THE QUESTION CAREFULLY!
If an expense is not allowable but has been deducted in arriving at the net profit figure, then it must be added back in the adjustment to profits calculation (to reverse what was done in the statement of profit or loss).
The treatment of some expenditure is different depending on whether the CASH BASIS or the ACCRUALS BASIS is being used.
Capital expenditure
on land and buildings is not allowable.
depreciation and losses/profits on sales are not allowable.
a repair to an asset is revenue expenditure and is allowable.
improvement to an asset that qualifies as plant and machinery for capital allowance purposes is allowable under the CASH BASIS but is generally not allowable under the ACCRUALS BASIS.
Reliefs, such as qualifying loan interest payments (see Chapter 2) are not allowable as they are dealt with as a deduction from total income.
Irrecoverable/Impaired Debts (Trade debt write offs & allowances)
Trade debt write offs and movements in specific allowances are allowable under the ACCRUALS BASIS, however non-trade write offs are not allowable.
Under the CASH BASIS, as income is only accounted for when received, then bad debts will not arise in the accounts.
Entertaining and gifts
entertaining is disallowed, unless entertaining employees.
gifts to employees are allowable but may be included as an assessable benefit within employment income for the employee - see Chapter 9.
gifts to customers are only allowable if;
they cost less than £50 per person per year, and
the gift is not food, drink, tobacco or vouchers exchangeable for goods and services
the gift carries a conspicuous advertisement for the business.
Subscriptions and donations
trade or professional association subscriptions are allowable,
charitable donation (not made under Gift Aid);
if it is small and made wholly and exclusively for trading purposes (e.g. promoting business’ name), and it is to a local charity then it is allowable.
national / international charity donations are not allowable.
charitable donations (made under Gift Aid) are not allowable.
Political donations - these are not allowable.
Legal and professional charges
disallowable if the item to which they relate is disallowable (e.g. land and buildings).
If related to an asset that qualifies as plant and machinery for capital allowance purposes, then allow under the CASH BASIS, but disallow under the ACCRUALS BASIS.
Allow if connected with the trade, e.g. drawing up staff contracts etc.
specifically allowed by statute:
costs of obtaining loan finance for trading purposes
costs of renewing a short lease (50 years or less)
Interest payable
interest paid on borrowings for trading purposes is allowable.
Lease rentals on cars with CO2 emissions exceeding 50g/km
Under the ACCRUALS BASIS, the disallowed amount is 15% of the leasing charges p.a.
Under the CASH BASIS, the whole amount is allowable.
Premium paid for the grant of a lease
the premium itself is disallowed as is any amortisation of the premium.
the allowable amount for each year of the lease is:
51 – n | × Premium |
50 | |
n | |
where n is the number of years of the lease.
Fines and penalties - Disallowed unless a parking fine paid on behalf of an employee and incurred whilst on business.
The accounting profit must be adjusted for the private expenditure of the business owner. For example, if the owner uses a car in the business but 20% of his mileage is for private journeys, then only 80% of motor expenses are allowable.
However if the owner provides an employee with a car, and 20% of the mileage is for private use by the employee, then the full amount of motor expenses is allowable. (The employee is then taxed on the private use as employment income - see Chapter 9).
Any deduction described as the owner’s salary, or drawings or interest on capital invested in the business is disallowed.
Interest paid on overdue tax is not deductible and interest received on overpaid tax is not taxable.
Any salary paid to the family of the owner of the business must not be above the normal commercial rate for the job.
Only salary at the commercial rate for the work done is allowable, any excess is added back.
If an owner removes goods from the business for his own use, then under the ACCRUALS BASIS he is treated as making a sale to himself at market value.
If the transaction has not been recorded in the accounts, then add in the selling price.
If the transaction has been recorded in the accounts at cost price, then add in the profit.
Under the CASH BASIS, If the transaction has not been recorded in the accounts,then add in the cost price. If the transaction has been recorded in the accounts at cost price, then there is no adjustment needed.
(p) Pre-trading expenditure – allowable if it is expenditure incurred in the seven years before the business commences to trade then it is treated as an expense incurred on the day the business starts trading and follows the above rules.
4 Fixed/flat rate expenses (cash basis and accruals basis)
In respect of cars, instead of claiming capital allowances and running costs, the trader may instead use a fixed (or flat) rate deduction for tax purposes. The actual capital cost of acquiring a car for use in the business, the running costs and the sale proceeds are excluded from the profit calculation.
The trader can instead claim as a deduction against the trading profit a mileage allowance for the business mileage. The allowance is at a rate of 45p per mile for the first 10,000 business miles and 25p thereafter. This replaces all costs of the car (with the exception of parking and toll roads).
Other flat rate expenses:
Premises used as both home and business premises such as a small hotel, guest house, bed and breakfast or public house can elect to claim a flat rate private use adjustment to apply in respect of private use of the property for such expenses as food, heat and light rather than attempting to compute a business/private split of the expenditure. Initially, all these costs are deducted and the flat rate private use adjustment is added back. Note this is an add back not a deduction.
The relevant flat rates will be provided in an examination question and are based on the number of occupants. For example if the property had one occupant the add back would be £350 per month or part thereof (£4,200 per annum) and for two occupants it would be £500 per month (£6,000 per annum).
The flat rate add back does not include other property expenses such as rent or loan interest payments.
On 1 April 2025 Jeremy started to trade, running a retail clothing shop, and has elected to use the accruals basis. Jeremy’s statement of profit or loss for the year ended 31 March 2026 is as follows:
£ | £ | ||
Gross Profit | 140,880 | ||
Expenses: | |||
Depreciation | 4,760 | ||
Light and heat (Note 1) | 1,525 | ||
Motor expenses (Note 2) | 4,720 | ||
Professional fees (Note 3) | 2,300 | ||
Rent and rates (Note 1) | 3,900 | ||
Repairs and renewals (Note 4) | 5,660 | ||
Sundry expenses (Note 5) | 2,990 | ||
Wages and salaries (Note 6) | 84,825 | ||
110,680 | |||
Net profit | 30,200 |
Notes
Note 1: Private accommodation
Jeremy and his wife live in a flat above the shop. Of the expenditure included in the statement of profit or loss for light, heat, rent and rates, 40% relates to the flat.
Note 2: Motor expenses
During the year ended 31 March 2026, Jeremy drove a total of 12,000 miles, of which 9,000 were for private journeys. He does not claim the fixed rate mileage allowance.
Note 3: Professional fees
Professional fees are as follows:
£ | |
Accountancy | 700 |
Legal fees in connection with the purchase of the clothing shop | 1,200 |
Trade debt collection | 400 |
2,300 |
Included in the figure for accountancy is £250 in respect of advice on inheritance tax planning for Jeremy.
Note 4: Repairs and renewals
The figure of £5,660 for repairs and renewals includes £2,200 for decorating the clothing shop during July 2025, and £1,050 for decorating the flat during August 2025. The building was in a usable state when it was purchased.
Note 5: Sundry expenses
The figure of £2,990 for sundry expenses, includes £640 for gifts to customers of food hampers costing £40 each, £320 for gifts to customers of pens carrying an advertisement for the clothing shop costing £1.60 each, £100 for a donation to a national charity, and £40 for a donation to a local charity’s fete. The fete programs carried a free advertisement for the clothing shop.
Note 6: Wages and salaries
The figure of £84,825 for wages and salaries includes the annual salary of £15,500 paid to Jeremy’s wife. She works in the clothing shop as a sales assistant. The other sales assistants doing the same job are paid an annual salary of £11,000.
Note 7: Goods for own use
During the year ended 31 March 2026, Jeremy took clothes out of the shop for his personal use without paying or accounting for them. The cost of these clothes was £460, and they had a selling price of £650.
Note 8: Plant and machinery
The capital allowances available for the year ended 31 March 2026 are £13,060.
(In the actual examination you will be required to prepare a capital allowances computation and work out this figure. - see Chapter 5)
Calculate Jeremy’s tax adjusted trading profit for the year ended 31 March 2026.
Show answerHide answer
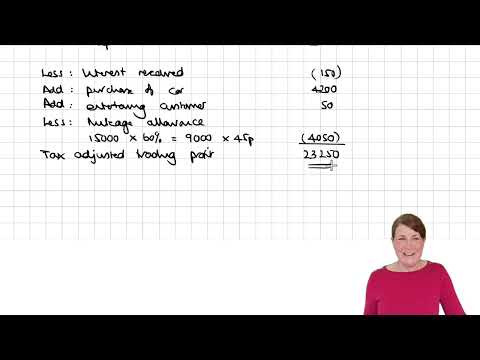
Giles started to trade as a sole trader on 1 April 2025.
The receipts figure in his accounts for year ended 31 March 2026 is as follows:
£ | ||
Cash receipts from customers | 20,000 | |
Bank transfers from customers | 38,000 | |
Cash receipt from sale of machine | 2,500 | |
Interest received on bank account | 150 | |
Total receipts | 60,650 |
The expense payments figure is as follows:
£ | ||
Cash payments for suppliers of goods for resale | 1,200 | |
Bank transfers for purchase of goods for resale | 22,000 | |
Standing orders to utility companies | 6,800 | |
Bank transfer for purchase of car | 4,200 | |
Cheque payment for machinery | 2,900 | |
Petty cash payment for entertaining customer | 50 | |
Interest on bank loan | 300 | |
Total payments | 37,450 |
The car has CO2 emissions of 85g/km and is used 60% of the time for business purposes. Giles drove 15,000 miles in the year and claims the fixed rate mileage allowance in respect of the car.
Calculate Giles tax adjusted trading profit for the year ended 31 March 2026.
Show answerHide answer
As this topic is more likely to appear as a Section B or C question where you have to adjust profits, there may not be many questions in Section A (MCQ)
However, a MCQ might look as follows:
In exam questions, in Section C, students are required to put in a zero adjustment for any items that do not require an adjustment to ensure that students deal with all items on the profit and loss account.
The wording might be as follows:
Note: You should indicate by the use of zero (0) any items which are not taxable or deductible.
The same style of proforma is used for sole traders, partnerships and Limited Companies and is highly examinable.
Learn the proforma.
And read the question carefully.