
The Auditor’s Report 3: Types of Audit Opinion


1 Unmodified opinion
Now we are going to look at the different forms of audit opinion and how other matters relevant to understanding the financial statements are drawn to users attention.
First and simplest is the unmodified audit opinion. This is the audit opinion that you will see in most auditor's reports. It simply states that the financial statements ‘present fairly’. There are no ‘ifs’ or ‘buts’.
An auditor's report with an unmodified opinion may, however, include any (or all) of the following additional sections:
‘Emphasis of matter’ paragraph;
‘Material uncertainty related to going concern’ section;
‘Other matter’ paragraph.
These matters do NOT affect the audit opinion.
2 Modified audit opinions
With respect to modified opinions there are two potential reasons for modification:
The financial statements include one or more material misstatements; or
The auditor has been unable to obtain sufficient appropriate audit evidence.
There are two degrees of seriousness for each of these problems.
First let’s look at material misstatement. This is where the auditor disagrees with the figure in the financial statements. It could be the figure itself or the way the figure is presented or the disclosures which must be made to comply with IFRS. First of all, if the misstatement is not material the audit opinion would not be modified, so the first hurdle is a that disagreement must be for a material amount. In such a case the auditor would put a paragraph in the report saying that except for certain items, in other respects the financial statements are presented fairly (i.e. the opinion has been qualified).
If however misstatements are so significant that it renders the financial statements as a whole useless, the auditor would issue an adverse opinion stating that the financial statements are not presented fairly.
The other reason for a modified opinion is where the auditor has been unable to obtain sufficient appropriate audit evidence.
For some reason the auditor has not been able to get all the information required to draw conclusions. If the matter about where there is missing information is material then the auditor will qualify his opinion using an except for paragraph. For example, except that we could not verify the adequacy of the trade receivables allowance (i.e. for irrecoverable balances), the financial statements are presented fairly. If, however, the missing information is so significant that the auditor is unable to form any opinion , the auditor gives a disclaimer of opinion
The choices can be described in a matrix. Think of ‘pervasive’ as misstatements or lack of evidence that affect the financial statements as a whole:
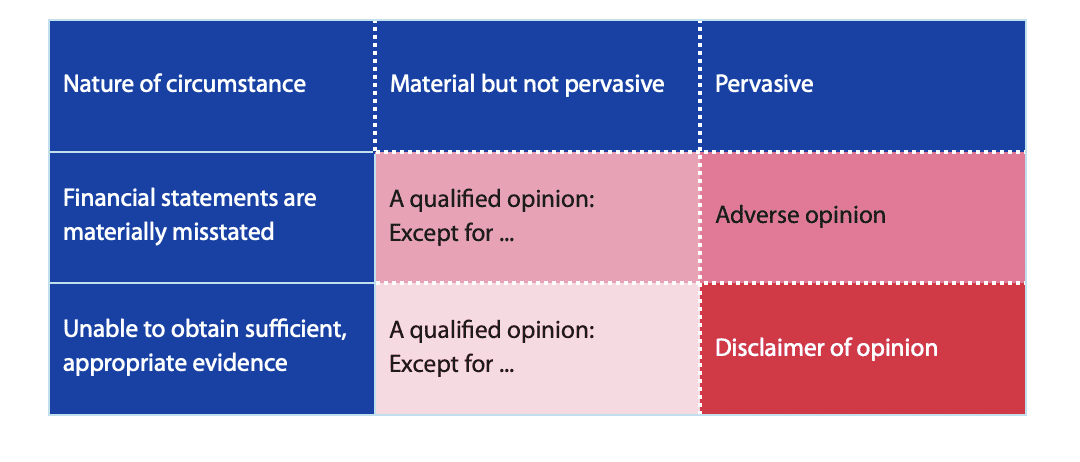
Nature of circumstance | Material but not pervasive | Pervasive |
|---|---|---|
Financial statements are materially misstated | A qualified opinion: | Adverse opinion |
Unable to obtain sufficient, appropriate evidence | A qualified opinion: | Disclaimer of opinion |
3 Example of insufficient appropriate audit evidence
Here is an example of a qualification due to insufficient appropriate audit evidence. Here the problem is material, but does not affect the financial statements as a whole and the report says the auditors are unable to determine the inventory quantities and then says in their opinion, except for the effects of such adjustments for inventory, if any, the financial statements are presented fairly.
Qualified Opinion (extract)
In our opinion, except for the possible effects of the matter described in the Basis for Qualified Opinion section of our report, the financial statements present fairly, in all material respects...
Basis for Qualified Opinion (extract)
We were unable to obtain sufficient appropriate evidence about the carrying amount of inventories because we were unable to attend the count of physical inventories at 31 December 20X1. Consequently, we were unable to determine whether any adjustments to this amount was necessary.
4 Example of disclaimer of opinion
Here is a modified opinion arising from lack of sufficient appropriate audit evidence but which is leading to disclaimer of opinion because multiple elements of the financial statements are affected.
Disclaimer of Opinion (extract)
We do not express an opinion on the accompany financial statements. Because of the significance of the matter described in the Basis for Disclaimer of Opinion section of our report, we have not be able to obtain sufficient appropriate audit evidence to provide a basis for an audit opinion on these financial statements.
Basis for Disclaimer of Opinion (extracts)
We were not appointed as auditors of the Company until [date] and thus did not observe the physical inventory counts at the beginning and end of the year...
In addition, the introduction of a new computerised system in [date] resulted in numerous errors in accounts receivable. As at the date of this report ...
5 Material misstatement/‘except for’
Here is an example of a qualified opinion arising from a material misstatement about something in the financial statements. Here the problem is that no depreciation has been provided when it should have been. Note, where there is a material misstatement auditors will normally be able to quantify its extent and the effect on the profits and this is useful information for the primary users of the financial statements. Here the amount of depreciation in dispute is material, but the financial statements as a whole are presented fairly.
Qualified Opinion
We have audited ...
In our opinion, except for the effects of the matter described in the Basis for Qualified Opinion section of our report, the accompanying financial statements present fairly, in all material respects …
Basis for Qualified Opinion
The Company's property, plant and equipment is carried in the statement of financial position at $xxx. Management has not depreciated ... which constitutes a departure from IFRSs. The Company's records indicate that had management depreciated ..., the company would have recognised depreciation of $xxx in the statement of profit or loss ... The carrying amount... in the statement of financial position would have been reduced by the same amount ....
6 Material misstatement/‘adverse opinion’
Finally, a modified opinion when one or more material misstatements are so significant that the auditor concludes that the financial statements are not presented fairly. Here the matter in dispute is the basis of accounting used in the preparation of the financial statements which is clearly pervasive.
Adverse Opinion
We have audited ...
In our opinion, because of the significance of the matter described in the Basis for Adverse Opinion section of our report, the accompanying financial statements do not present fairly ...
Basis for Adverse Opinion
The Company's financing arrangements expired ... and is considering filing for bankruptcy ... a material uncertainty exists... The financial statements do not adequately disclose this fact ...