
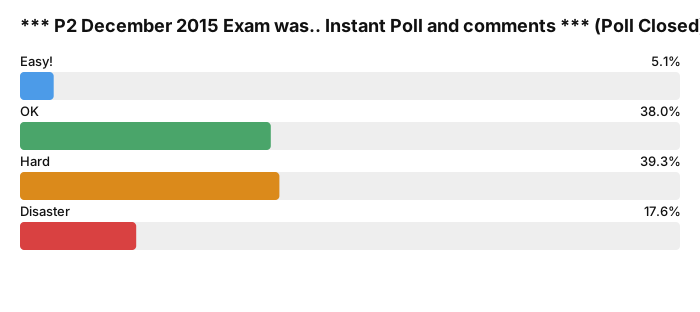
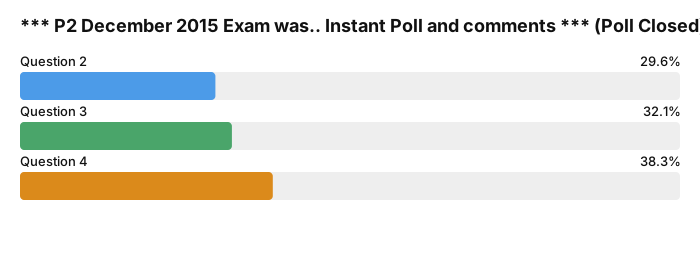
Please vote in our Instant Polls about the P2 December 2015 Exam.
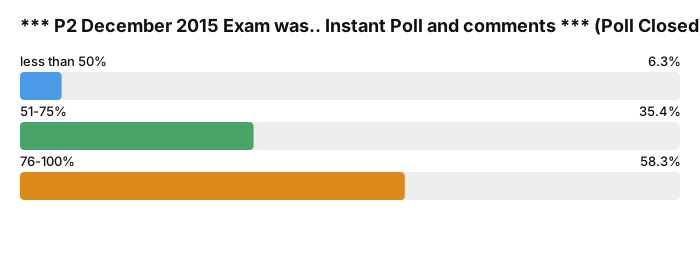
 Post your comments about P2 exam below
ACCA Forums
Post your comments about P2 exam below@kilmovee said: I would like to refer you to pg 366 section 3.4.4 the contingent liability according to the bpp manual should be included. Therefore 16 is the correct answer.It's good when we can give reference; but the basic for contingent is disclosed - not recognized. Once it becomes probable it's a provision and no longer contingent. The answer will assist us - do not believe - the possibility is out for typro errors. When we share something like this - it enhance learning if we participate with the intention to learn - not to be a winner. There are three basic points in the questions - indicating the transactions status and we should not be confused with the actions that was done prior; but do whatever proper accounting principles permits. I hope everyone - even through you may have pass the paper, take the requisite steps to improve knowledge - constant reading is important. We must recite the standards - the next job interview or appraisal my just test how sharp you're. Do not underestimate anyone. This makes it even more - USA is agreeing with ACCA, the world is coming together as a village. The competition with some certifying body will soon be over; so we must be up-to-date with information - sharing same with others. The result date - January 18, 2016 you can further share - green_452@yahoo.com Regards,
 Former user10y ago#122
@joevassallo said: I agree entirely with you - as far as I know the fair value of the contingent liability should be included with the Net Asset calculations (both at acquisition and reporting dates). The question said it was "disclosed" previously at $5 (i.e. not recognised in the Accounts but shown as a Note in the Accounts). But then it had a fair value of €1m... Besides I am not quite sure I understood paragraph 3 of email sent from Cardine, and what message is he trying to convey???Joe - Paragraph three (3) is sharing an experience I've in an interview. The job was for a finance manger based in southern side of USA; it's for a number of contract projects the the organization will under go with partnership with local and overseas organization - UN, world bank etc. They ask a question which relate to the new IFRS 15; I answer making specific reference to the changes that will take effect January 2016 - they ridicule me. It's obvious that they were not aware of pending changes as it relate to contract - I did not get the job. I wrote to them - sending to the head of finance extract from the new procedure and how we should treat revenue and expense in a contractual agreement. Some people are not comfortable when people they look-down on has more information than they do. We do NOT do this on this NOBLE forum - we're the best; OT set the pace and we MUST continue to share opinion - this is a tool for professional development. I love all the response - its challenges bring result in knowledge acquired. Hold your points and stand for what you know. Even if you're ridicule - it's your right to state facts and express your opinion!!!!!!!!!!! Peace, love and blessing on ALL colleagues - exam success!!!!!!! Happy holiday(s) for everyone!!!!!!!!!!!Continue with preparation - March/June 2016, we'll reap the fruit from our labour - goooooooooood things!!! Regards,
@sharique123 said: Kindly reply. I will be really thankful. The next exam session of March 2016 will be a mix of March 2016 and June 2016 session. Is my undrestanding correct ?Hi Colleague; If you read the ACCA policy - new exam and the recent past paper being published, you'ld have agreed: ACCA replicates aspects of September in the December exam; therefore the past paper for the early secession was not available. The comment this forum confirm - P2 question #2 was from the September sitting; therefore, it wised move to redo the questions with help from your notes. We should not be depending on whether questions will be repeated; but know the syllabus to answer ALL questions correctly - equivalent to pass mark achieve. I presumed - March is the first print and June will carry aspect of March; Therefore - March/June Past papers read: September/December and I believe after reading the policy it is March/June. This makes it easier for one to succeed at resit - if you worked the questions following the exam - June or December. The two new secession papers will be TOP secret - multiply choice questions answer will of the past - see policy on site. Regards,