Skip to content

MA1

Labour - Gross and net earnings

CAT MA1 Course Notes Contents Page
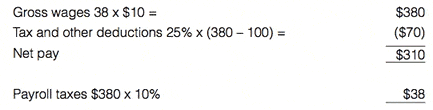
Gross and net earnings

  • Gross pay: the total amount earned by the employee
  • Net pay: the amount paid to the employee after the employer makes deduction for income tax and certain statutory amounts.
  • Total labour cost to employer: employees’ gross pay plus any additional payroll taxes (and perhaps pension costs) that the employer has to bear.
  Example 2  An employee is paid at the rate of $10/hour. Tax and other deductions amount to 25% for weekly income in excess of $100 Employer payroll taxes = 10% gross wages If an employee works 38 hours in a week, what are the employee’s gross pay, net pay and the total amounts that have to be paid by the employer to the tax authorities?

Answer to Example 2

Example 2 Gross and net earnings   Total payments by employer to tax authorities = $70 + $38 = $108  
Accounting for labour costs

In addition to being paid whilst working (basic, overtime premiums, productivity bonuses, employees are often also paid when:
  • on holidays
  • ill
  • idle (because, say of machine breakdown)
The labour costs are classified as direct or indirect depending on what caused those costs: Direct labour costs: all hours worked x normal hourly rate Indirect labour costs: overtime premium, idle time, sick pay, holiday pay. In double entry, the system is as follows: Dr Work-in-progress with the gross wages Cr Wages control account with the gross wages   Dr Work-in progress with the employer’s payroll tax Cr Wages control account with the employer’s contributions to payroll tax   Dr Wages control account CR Cash as employee paid the net amount CR Cash as the revenue authorities are paid employee deductions and employer contributions.  

Example 3 

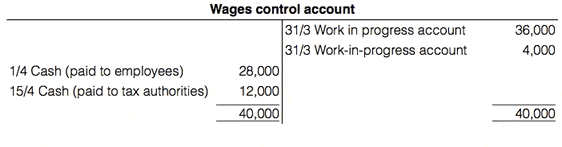
Show the following transactions in wages control account
  1. 31 March, gross wages calculated as $36,000; deductions for employees taxes = $8,000
  2. 31 March, employer’s payroll tax calculated as $4,000
  3. 1 April, employees paid amounts due
  4. 15 April, tax authorities paid amounts due
 

 Answer to Example 3

Example 3 Employee remuneration  

3 Comments

  1. mantibilili
    assist with above question
  2. veejaytha
    cant we have a video for this chapter???
  3. John MoffatTutor
    We do not have videos for Paper MA1.

    However we do have videos for Paper FMA/MA and Accounting for Labour is one of the Paper FMA topics.

Leave a comment