SBR*** P2 December 2015 Exam was.. Instant Poll and comments ***
Oopentuition_teamAdmin10y ago
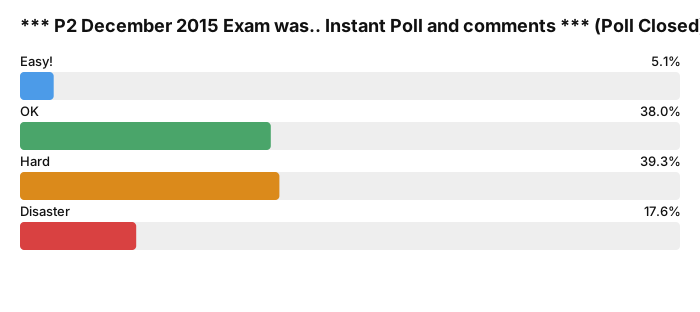
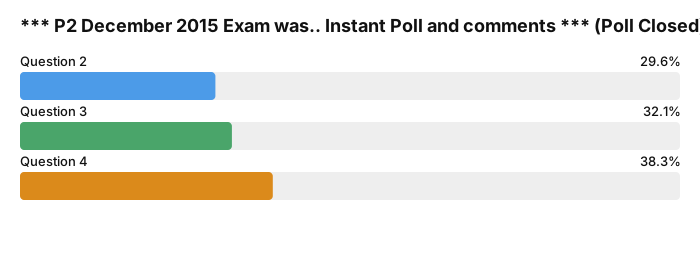
Please vote in our Instant Polls about the P2 December 2015 Exam.
Post your comments about P2 exam below
SShane10y ago#1
So, the lease on Q2, although it was a lease of land, I went with finance lease. Anyone else agree??
Ddjgard2710y ago#2
Yes I thought the same a finance lease. what other question did you do? I couldnt decide between question 3 or 4. I went for 3 but i hope i dont regret it I think 4 would have been more straightforward never mind its done now.
AAhmed10y ago#3
Time management was a serious issue in this paper
AMAhmed Mirza10y ago#4
Finance lease:
I think because of the specialised nature of the asset and in case of cancellation the lessee had to bear the costs
AMAhmed Mirza10y ago#5
Time management is the challenge. I just hope I pass.
Nnish8110y ago#6
It appeared to be a finance lease but it was an operating lease
FFakhry10y ago#7
What a bout Q3 4 is it joint operation ?
DDhaval10y ago#8
I put it down as an operating lease, still unsure though..
FFakhry10y ago#9
Q3 a
Nnish8110y ago#10
It was an operating lease,the question was from the examiners article
AAhmed10y ago#11
What did people get for foreign subsidiary translation post acquisition retained earnings?
Former user10y ago#12
Q 1 was quite ok , but before calculating post acquisition reserve time is up , unable to complete b/s . would there b any problem for that.. Time management is a big challenege..
AAnil10y ago#13
I got 1.45 post aq reserves for the foreign sub.
I thought question 1 was fair but a lot of adjustments on the foreign PPE removal of staff costs, depreciation, profit on land disposal, revaluation gain.
Question 3a) was a joint operation should of equity accounted for it.
E.g take ur share of profit after deducting your share of expenses
Make a provision for the decommission costs at pv then unwind the provision each period. The decommission costs should have been depreciated .
3b) I thought was a financial instrument that should be measured at amortised value. As the payments that are usually for cash was replaced by gas. The payments of gas was of interest and principal. Thoughts?
3c) was strange the first part I wrote a provision should be made for parts but not for labour
The second part I wrote that the expenses should be expensed and not amortised as they are just research costs and no economic benefit is probable.
4a) the five step model for revenue for 13 marks which was great.
Part b)
I said the revenue should be deferred until control of the printer is transferred as the company pays in advanced but the asset transfers after two years.
B) was a weird one. I said the company should recognise 65% of revenue and costs but the change of the contract gave rise to an adjusting event as it would change the amounts recording in the financial statement as the percentage has now changed.
OOshan10y ago#14
How did you do that retirement obligation question ?
AAnil10y ago#15
That was tricky.
He gave a net obligation.
Which had an interest rate attached I used the start period interest rate and not year end. The net expense I took to retained earning.
The pensions paid to employees would have an entry of dr pension liability cr pension liability so it would have a NIL effect on the NET obligation.
There was a 3m gain on previous conditions that I dr obligation and cr retains earning.
Then there was an actuarial comment that stated that the pension was measured net at 17m the company only had recorded 15m in current liabilities I cr current liabilities 2 and took the remeassured amount to OCOE.
Please not I am not saying I am correct but this is what I did.
RRav10y ago#16
^^ Sorry but I got 6.5 for OCE, which was a debit to OCE and a Credit to the obligation.
Did anyone do question 2 a) licenses.
AAnil10y ago#17
Rav - how did u get dr ocoe 6.5 can I ask?
SShane10y ago#18
I read the examiner article and still come up with a F.L. conclusion..........
Ggreenzstarr10y ago#19
It was an operating lease. Remember, the asset was of a specialised nature but there will be no more capacity upon completion of its leased life therefore it will not be able to be employed for use. Also, the lessor (Government) is benefitting from the proceeds on any sale of the lease. The reward arising is therefore retained by the Lessor
AAnil10y ago#20
The pension plan was currently valued at 15m and then revalued to 17m so surely it would be a cr 2m non current liabilities
RRav10y ago#21
Well the opening obligation moves by Dr past service cost for curtailment, Cr current service cost, Dr contributions paid into pension, and Cr for interest based on bond rate.
That gave me a closing liability which was assessed to be 17 by the actuarists... 6.5 was the re-measurement component. Not saying that's correct but it's what I did.
I don't remember the exact numbers tbh.
OOshan10y ago#22
May I know how you did foriegn loan of foriegn sub?
RRav10y ago#23
The foreign loan was I/C so needed to be removed at it's closing liability from the net assets at reporting date.
That's how I treated it but again, probably wrong.
Nnish8110y ago#24
Where an asset has been leased several times during its economic life, and the lease is the last lease to take the asset to the end of its life, then many of the indicators may point towards a finance lease. For example, the present value of the minimum lease payments may approximate to the fair value of the asset at the inception of the final lease and there is unlikely to be an option to purchase the asset at fair value or to extend the lease at a market rent because the asset has reached the end of its life. However the asset will obviously be non-specialised and the final lease will not be for the major part of the economic life of the asset. The lease will be for the entire remaining useful life of the asset but IAS 17, Leases, focuses on economic life as an indicator of a finance lease. The lessor is recovering the investment in the asset through a number of leases and the substance of each of those leases will normally be an operating lease. Thus if the final lease were to be classified as a finance lease simply because of its position in the chain, this would normally be unacceptable. ?
FFakhry10y ago#25
Pension obligation at YE should be 17 plus 4 equal 21 this as net asset at year end is 4 and deficit is 17 .l guess
AAnil10y ago#26
I removed the foreign subsidiary loan and the asset from the company.
I removed the loan which the remaining amount was 40m dinars from non current liabilities before conversion.
Mmarigold0110y ago#27
@nish81 Can u pls paste the link to the examiners article for operating lease
SShane10y ago#28
I went with
op bal 15m
past service cost (p/l) 5m
Gain on Curtailment (p/l) (4m)
Contribution (6m)
Balancing figure to OCI 7m
Actuarial FV 17m
Figures may bee incorrect but I think I got my OCI figure of circa 6 or 7.......... I took the curtailment figure as referring to the Interest figure for some reason.......
RRav10y ago#29
@Nish, it wasn't the end of the economic life of the land. It could have had other use. They had just decided to sell it as it no longer fitted their intention as a dumping ground.
OOshan10y ago#30
But for the loan subsidiary has to identify exchange gain or loss at year end also. There is an effect of that. Can you plz explain?

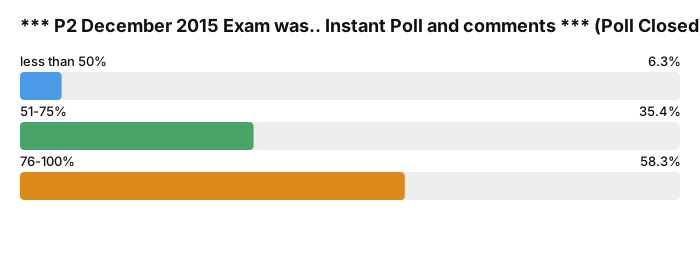
 Post your comments about P2 exam below
 Former user10y ago#12