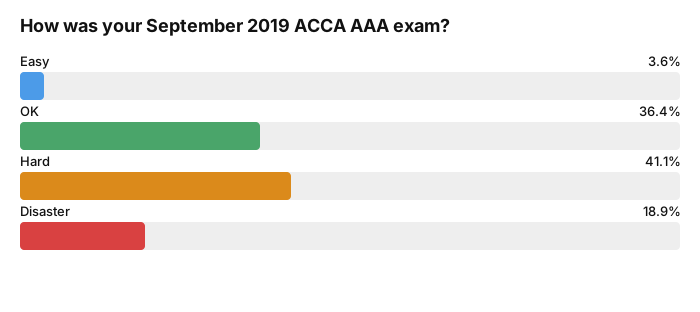
ACCA Forums
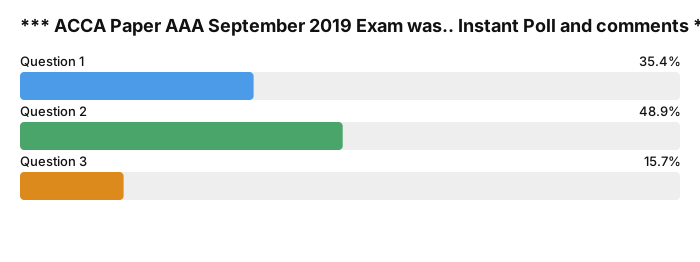
AAA*** ACCA Paper AAA September 2019 Exam was.. Instant Poll and comments ***
Well that was different!
It was a lengthy paper and a bit on difficult side. Not sure about Q3
24 marks for audit risk was crazy!! Discontinued operations & joint ventures - wow. Very different scenario to any past papers
Hmmm. The paper was surely a different type compare to past papers. Not confident to say whether its a pass or not. Will have to wait and see.
I struggled with question 2. I added the adjustments per scenario together to determine materiality, don't know if that's right or I royally messed up!
Q3 on forensic accounting I didn't find too bad. Especially the second part on internal control deficiencies, and recommendations.
I found Audit risks disaster. 24marks be hard to score even 12marks.
Q2. Tough but audit evidence not bad.
Q3. No clue forensic Audit.
The rest of question was ok to score marks
Again, a tough one, very time intensive (3rd attempt after 49 & 35).
Q1: agreed, so many audit risk marks, with apparent emphasis on disclosure. I missed easy marks on new client, but focussed on the acquisitions/ disposals, in respect of disclosure in group and individual FS. Hope I did enough to get 50% here. Spent too much time on this bit (and how much revision ‘wasted’ on financial analysis..!).
Q2: due to time pressure I left the Lease question, seemed very technical to get the marks. For part (ii) I said the classification of profit was incorrect - should be OCI upon initial recognition of Investment Property... leaving the final 5k to be credited to P/L at year end... hope that was correct! Either way, immaterial (unless disclosure required). Part (iii) I thought was OK- incorrect to recognise any income, as no costa incurred? Should be recognised in line with expenditure? So all deferred, and potentially some element discounted, depending on additional info about timing of expenditure..?
Q3: relatively straight forward, but only had 25min for this. Gutted I left this until the end, as so many easier marks available.
I previously sat Dec 18 & Mar 19... this ‘seemed’ more straight forward... fingers crossed for results day... final exam..!
Good luck everyone!
I thought the audit risk question only referred to disclosures in regards to the group restructuring and therefore everything else was a legitimate audit risk? For example the license should be classified as a intangible asset and amortised, the disposal of the burger company should have been classified as held for sale and so forth?
Audit risk - grant I think there were 5 marks in total here. 3 for the materiality, standard and risk of recognition of a grant and then another 2 for the risk the condition of the grant might not be met.
I also said the restructuring plans should be disclose as a note in the FS there is a risk of no disclosure or risk that the disclosure would not be adequate.
The licence of 15k was depreciated over 20 years, this should have been depreciated over the 3 years. Materiality and standard - 3 marks
Managent trying to recoup the capital expenditure of 43 - risk of manipulation and over statement of profit
That's right hits123, 24 marks just for disclosure would be nuts, so much info in that question, I forgot about over the licence, wrote about the massive 29% revenue growth of just 50 new coffee shops.
I feel like a complete numpty now not picking up on it being a new client and the joint venture, cripes. Hopefully I picked up good marks elsewhere, I'm confident I did well got Q3, but will only find out next month.
For Q1, is it possible that the company owning 50% might be a joint control ? Did anyone think about it and should be accounted for as a joint control, using equity method ? Also it it non adjusting event regarding disclosure ? I couldn’t come to a conclusion on that one.
Also did anyone talk about operating segments ?? 10% revenue and asset ???
Also the capitalization of the full $43, reconstructing cost may have some expenses that need to be expensed? Change in depreciation policy ?
Q3. Was it ok to use Assurance engagement preconditions as I didn’t read forensic audit even when my gut told me to.
.
I found this is a lengthy question, how time management helped me to answer all.
Audit risk question had so many risk. Procedure and ethical questions relatively easy.
Matter question bit tough but evidence would help to gain few marks.
Forensic question bit knowledgebase and procedure would help to gain additional marks.
Finger cross for exam result.
Can anyone tell me how it was recognised as a new client, i actually checked whether it was a new client and dint find any clues during when i was reading the question, feels dumb now
Very disappointed with my self. I prepared technically better this time but the time pressure most probably failed me. How can the examiner ask for evidences and I write procedures? December again!
I agree. I was pretty careful on looking out for whether it was a new client or not in the scenario given. I couldn’t find anything. I do remember reading on how I, the audit manager, was new to this group audit but nothing about the client being new to our firm.
Maybe I got it wrong, who knows. It was definitely a tough paper but can’t do anything but wait now :/
Ques 1 was quite complex..
Anyone remembers the 4 parts to question 1 and the mark scheme?
24 pts on audit risks, 4 marks additional information, 8 marks procedures, 10 marks on ethics & 4 marks professional marks
How can you answer 24 marks on audit risks based on disclosures? I think there is no reason bothering with this qualification . Totally unreasonable . It’s all about confusing people to fail 70% every sitting and label themselves as a difficult to achieve qualification! Rubish
There was nothing in Q1 that said it was a new client, it said the acquisition was a newly formed company not that the group was a new client. i was careful to check this as easy marks for audit risk! There were disclosures needed such as operating segments, discontinued operations. This exam was very different to past mock exams, lots of standards to discuss, i sat the UK version and i expect there wasn't any difference between the International version due to the questions not being related to country specific ISA's
@ajiljacob96 said: Can anyone tell me how it was recognised as a new client, i actually checked whether it was a new client and dint find any clues during when i was reading the question, feels dumb nownot just you I actually checked but couldn't see the place where it stated that it's a new client. I also missed some easy marks on complexity due to restructuring, consolidation risks and the other easy bits. The 24 marks was just too much to grab
It was not a new client, only the new investment was tagged new.
From what I remember these were the questions and marks available:
Q1
Audit risks (24)
Additional information on disposal (4)
Procedures for a) joint venture classification, b) government grant (8)
Ethical and professional issues (10)
Professional marks (4)
Q2
Matters to consider
a) Sale and leaseback (8)
b) Investment property (6)
c) Impairment of mall (6)
Audit opinion (5)
Q3
Accepance of forensic audit (8)
What evidence needed to get value of fraud (6)
Criticism of controls and improvements to suggest (6)
Why auditors can't always detect fraud (5)
All in all this paper was awful. No easy business risk marks, instead a nightmare scenario with a group with held for sale assets, joint ventures, planned future acquisitions, restructuring, and a requirement to talk about disclosures which I've never seen in any past questions...
Matters and evidence - the sale and leaseback was a mess, I have no idea what they did right or wrong. The others were okay, but the inclusion of a load of figures for the impairment was hard to deal with whilst sticking to the timeframe - I don't see how anyone has the time to calculate part-year depreciation and/or impairment adjustments. Why not the usual short scenario with accounting explanations required, instead of tables of numbers to take into account in the few minutes you have to read it.
The final question being on forensic auditing also threw me. I couldn't quite get my head around the mechanics behind the fraud, so couldn't explain how to analyse it beyond generic "use CAATs to analyse transactions", and controls criticism was also a bit weird.
All in all I never felt like I really knew what I was on about except for a couple of questions in Q2, but I did manage to write something for everything, so there's an outside chance I pick up enough marks here and there to pass. If not, at least I know the resit can't possibly be this hard.
the question says significant audit rise and disclosure risk. So everything is not disclosure is the combination
Q1 I found the 24 marks question really difficult for an audit risk question. The disclosure on the restructuring made it really hard. I eventually missed simple group audit risks like how complex the business was, the consolidation risks and the like. Restructuring had a lot of risks to identify.Joint ventures maybe for the new company, discontinued operations not properly presented, fair value risks etc. For new coffee shops Capitalization of intangibles and wrong amortization of 15k 3years intangibles for the new shops and probably contains expenses that should be expensed. Government grant there was bias to boost earning should be in OCI maybe. Materiality to P&L and SoFP. Question for additional doc requested easy 4 marks. Audit procedures easy 8 marks. Ethical issues were very evident in the scenario so quite good. Hope I get 70 percent of question one.
Q2. Very difficult.. Disaster. Evidence will probably help a bit. Sale and lease back I felt was correctly treated. Investment property not properly valued Ias 36 misapplied. Not material though to PandL. Shopping mall amortization reversal didn't see what was wrong just saw a lot of back and forth with the estimates. Since it was material I wrote what I could. Evidence again to the rescue. 2B effect on audit report I did separately then combined. Since shopping mall was significant and pervasive on all FS I suggested adverse opinion and basis for adverse.
3. Forensic audit was the only nice question here but unfortunately time pressure had set in. First part just needed points about accepting the engagement. Competence, independence if audit client, if the report will be used for legal proceedings etc. Cool 8 marks. Procedures for quantifying inventory lost due to fraud... Ehhh kinda hard. Listed interviews, CAAT, recalculation and some control testing. 6 marks maybe I'll get 4. Internal control deficiencies were very obvious so cool 6 marks. Last 5 marks was about mgt and the company's auditors reaction to the discovered fraud. I blamed the mgt for weak controls but also blamed the auditors for not testing controls that resulted in mistatements in the FS. Explained how the ISAs required auditors to be sceptical and that it's not their duty to prevent fraud but should have reported and discovered deficiencies also if they have caveat in their report it could help. Too much talk for a 5 mark question but time was almost up and I wanted to do the one I felt confident in while sulking on question 2.
@jecksmelv said: Q1 I found the 24 marks question really difficult for an audit risk question. The disclosure on the restructuring made it really hard. I eventually missed simple group audit risks like how complex the business was, the consolidation risks and the like. Restructuring had a lot of risks to identify.Joint ventures maybe for the new company, discontinued operations not properly presented, fair value risks etc.You've just made me realise so many easy marks I failed to get whilst worrying instead about the disclosures for the restructuring... Why didn't I just go back to basics and talk about complex group (1 mark), consolidation risk (1 mark), high revenue increase for the coffee drive throughs (1 mark)...
Did anyone else pick on if the depreciation was corrected and if the grant corrected then the company actually ran at a loss?
I wrote evidences like a copy of etc etc instead of additional information required in Q1. Do you think I'll get marks for that ?
In regard to the sale leaseback of the property I don’t necessarily agree with the accounting treatment as in my opinion it should not have accounted for as a sale under IFRS 15 albeit that they were only leasing the asset for 10 years with its useful life being estimated beyond 50 years. This is because the entity still bears the risks and rewards for the property regardless of the lease period and therefore the entity should not have derecognised the asset and instead recognised a right of use asset and a lease liability as well as depreciating the asset over the shorter of its lease term and useful economic life and in this case it would have been the lease term of 10 years.
Topic lockedNew replies are closed.