
MA1
Inventory and valuation of closing inventory
CAT MA1 Course Notes Contents Page
 Note:
Sales do not alter the average cost.
Receipts and sales are handled on a strict time basis.
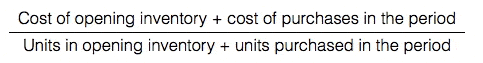 So, all units used in the period will have the same cost.
In the above simple example this method would give the same result as the cumulative weighted average approach
 Calculate the cost of inventory used each time and the cost of the inventory remaining at the end of the period using:
 Cost of sales = $1,067 + $6,463 = 7,530
Closing inventory = $3,770
Periodic weighted average
Value of purchases plus opening stock = $5,000 + $3,000 + $3,300 = $11,300
Units purchased plus in opening stock = 1,000 + 500 + 600 = 2,100
Periodic average = 11,300/2,100 = 5.381
Cost of sales = (200 + 1,200) x 5.381 = 7,533
Value of inventory = 700 x 5.381 = 3,767
Different methods used to price materials issued from inventory and to value closing inventory
Consider the following: 12 March 20X4: buy 1000 units at $5 each 21 March 20X4: buy 500 units at $6 each 31 March 20x4: sell 800 units at $12 each. Clearly revenue will be 800 x $12 = $9,600, but what is the cost of the units sold? Which have been sold? What is their value and the value of the inventory left?You have to know four approaches:
- FIFO
- LIFO
- Cumulative weighted average
- Periodic weighted average
FIFO (First-in, first out)
This method assumes that the goods that arrive first are the first to be used. It is only an assumption: apart from their price all goods of a given type are identical and therefore you don’t know, or care, how they are physically used. So, in the above case, all 800 units sold would be assumed to be those delivered on 12 March. They would have a cost of 800 x $5 = $4,000 and the value of the inventory remaining would be 200 x $5 + 500 x $6 = $4,000. Note that receipts and sales are handled on a strict time basis.LIFO (Last-in, first out)
This method assumes that the goods that arrive last are the first to be used. As before It is only an assumption: apart from their price all goods of a given type are identical and therefore you don’t know, or care, how they are physically used. So, in the above case, the 800 units sold would be assumed to be all 500 of those delivered on 21 March plus 300 from the March 12 delivery. They would have a cost of 500 x $6 plus 300 x $5 = $4,500, and the value of the inventory remaining would be 700 x $5 = $3,500. Note that receipts and sales are handled on a strict time basis.Cumulative weighted average
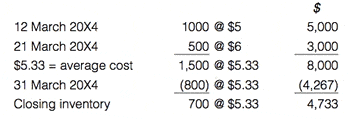
Every time units are added, a new average price is calculated. Any time goods are removed they are removed at the prevailing average. 12 March 20X4: buy 1000 units at $5 each 21 March 20X4: buy 500 units at $6 each 31 March 20x4: sell 800 units at $12 each.
Note:
Sales do not alter the average cost.
Receipts and sales are handled on a strict time basis.
Periodic weighted average
Here, a new inventory value is calculated at the end of a set period. The cost of goods used is given by:
So, all units used in the period will have the same cost.
In the above simple example this method would give the same result as the cumulative weighted average approach
Example
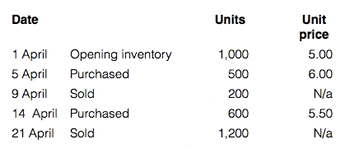
Recent results of a division are:
Calculate the cost of inventory used each time and the cost of the inventory remaining at the end of the period using:
- FIFO
- LIFO
- Average cumulative cost
- Periodic average cost
Answer to example
FIFO Sale of 200 on 9 April: assumed to be units from opening inventory: 200 @ $5 = $1,000 Sale of 1,200 on 21 April: assumed to be the 800 remaining from opening stock plus 400 from the purchase on 5 April: 800 @ $5 + 400 @ $6 = $6,400 Closing inventory will be all the 600 purchased on 14 April plus 100 left from the 5 April purchase = 600 @ $5.50 + 100 @ $6.00 = 3,900. LIFO Sale of 200 on 9 April: assumed to be units purchased on 5 April: 200 @ $6 = $1,200 Sale of 1,200 on 21 April: assumed to be the 600 from the purchase on 14 April (600 x 5.5 = $3,300) plus 300 remaining from the purchase on 5 April: 300 @ $6 = $1,800, plus 300 from opening stock @$5 = $1,500. Total cost of those sales = $6,600 Closing inventory will be all from opening stock: 700 @ $5.00 = $3,500 Cumulative weighted average
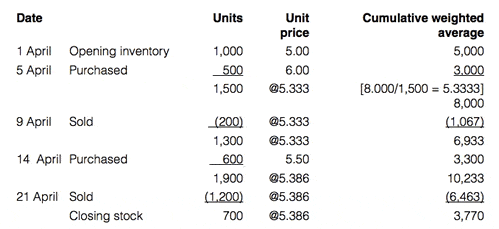
Cost of sales = $1,067 + $6,463 = 7,530
Closing inventory = $3,770
Periodic weighted average
Value of purchases plus opening stock = $5,000 + $3,000 + $3,300 = $11,300
Units purchased plus in opening stock = 1,000 + 500 + 600 = 2,100
Periodic average = 11,300/2,100 = 5.381
Cost of sales = (200 + 1,200) x 5.381 = 7,533
Value of inventory = 700 x 5.381 = 3,767
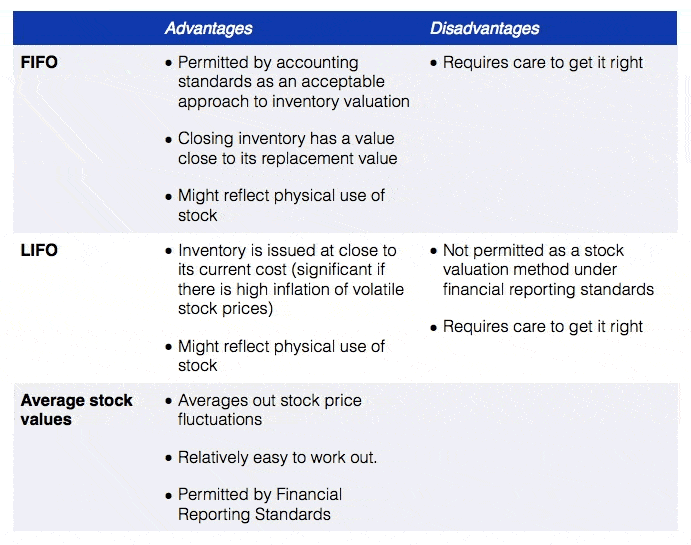
Advantages and disadvantages of the methods:
P Q
Purchase cost 100 200
Delivery costs from supplier 20 30
Delivery costs to customers 22 40
Coloured sales packaging costs 15 18
Selling price 150 300
Required:
Calculate the figure to be included in closing inventory for a unit of each model; according to IAS 2.
Help please)